Category: money

  • Should I Pay Off Debt or Build an Emergency Fund First?

    Should I Pay Off Debt or Build an Emergency Fund First?

    You have a little extra money. Should you put it toward your credit cards or save it for the next emergency? Let’s talk about how to decide.

    If you have high-interest debt and little or no emergency savings, the best answer is often to do some of both. A small emergency fund can help keep an unexpected expense from becoming more debt, while paying extra toward high-interest balances can reduce the amount you spend on interest.

    But how much should you save before focusing on debt? And does it make sense to keep money in savings when your credit card is charging 25% or 30% interest?

    Those are good questions. Let’s work through them.

    Why Is This Such a Difficult Decision?

    Imagine you’ve managed to put aside an extra $500. That’s good news. You have a little breathing room, and now you want to make the most of it.

    Your credit card has a $3,000 balance and charges 28% interest. You also have just $100 in savings.

    You could put the entire $500 toward your credit card. That would reduce your balance and save you some interest. Or you could put the $500 in savings. That wouldn’t reduce your debt, but it would give you some cash if your car broke down or you needed an unexpected prescription.

    Neither choice is unreasonable. The problem is that you’re trying to protect yourself from two different kinds of financial trouble. Your debt is costing you money right now. An emergency might cost you money tomorrow. The trick is finding a balance that helps with both.

    Should I Build an Emergency Fund While I Still Have Credit Card Debt?

    Usually, having at least a small amount of emergency savings is worthwhile, even when you’re paying off debt.

    Suppose you put every available dollar toward your credit card. You’re making progress, and that feels good. Then your car needs a $400 repair. You don’t have the cash, so you put the repair on your credit card. Now some of the debt you just paid off is back.

    That’s the problem an emergency fund helps prevent.

    You don’t necessarily need three or six months of expenses saved before you begin paying down expensive debt. But having some cash available can keep a manageable surprise from turning into another borrowing decision.

    If you’re starting with nothing, a first goal of $500 or $1,000 may be useful. Those are starting points, not universal requirements. Your actual target depends on your household, income, and likely emergencies.

    Someone with a stable paycheck and few unexpected expenses may need a different starting cushion than someone whose income changes every month or who depends on an older vehicle to get to work.

    But Doesn’t Saving Money Cost Me More in Credit Card Interest?

    It can. And this is where the numbers matter.

    Let’s use a simple example: a $3,000 credit card balance at 28% interest, $100 in emergency savings, and an extra $500 available.

    If you put that $500 toward your credit card, you could avoid roughly $140 in interest over a year, assuming that $500 would otherwise remain outstanding for the entire year at the same rate.

    If you put the $500 into a savings account earning 4%, it would earn approximately $20 over a year, assuming the rate stayed the same.

    From a strictly mathematical standpoint, paying the credit card wins. But if you have no emergency savings and something goes wrong, you may have to borrow again. Depending on your available credit and circumstances, you might not even be able to borrow when you need to.

    The goal isn’t just to pay the least interest possible. It’s to make your finances more stable so you can keep making progress.

    What Should I Do First If I Have No Emergency Savings?

    1. Can You Cover a Small Unexpected Expense?

    Could you pay for a flat tire? A minor plumbing repair? A prescription? An urgent trip to help a family member? If even a relatively small expense would force you to borrow, building a starter emergency fund deserves attention.

    2. How Expensive Is Your Debt?

    A credit card charging 29% interest is very different from a promotional credit card charging 0%. If you have several debts, list their balances, interest rates, and minimum payments. That makes it easier to see which balances are costing you the most.

    3. How Reliable Is Your Income?

    If your income is predictable and your essential bills are manageable, you may feel comfortable keeping a smaller emergency cushion while paying down debt aggressively. If your hours change, your income is seasonal, or your job situation is uncertain, having more cash available may be especially important.

    Should I Split My Extra Money Between Savings and Debt?

    You can, especially while you’re building your first emergency cushion.

    Let’s say you have an extra $200 each month after covering essential expenses and minimum debt payments. You might put $100 into savings and $100 toward your highest-interest credit card until you’ve built a starter emergency fund.

    Once you’ve reached that first savings goal, you could direct most or all of the extra $200 toward expensive debt. Some households may need to build cash savings faster. Others may already have enough savings to focus entirely on debt repayment.

    And remember, you still need to make at least the required minimum payments on your debts.

    Can I Use a Credit Card or Line of Credit as My Emergency Fund?

    If you have available credit, it may seem unnecessary to keep cash sitting in savings. Sometimes available credit can be a useful backup. But it isn’t the same as emergency savings.

    A lender may reduce your credit limit, freeze an account, or change borrowing terms under the agreement. And borrowing to handle an emergency creates a payment obligation that may come with interest.

    Cash savings don’t require approval, don’t add to your debt, and don’t create another monthly payment. I wouldn’t treat access to borrowed money as a complete replacement for money you already have.

    What If I’m Already Behind on My Bills?

    If you’re having trouble paying your mortgage, rent, utilities, insurance, or minimum debt payments, your priorities may need to change.

    Before putting extra money toward a credit card, make sure you’re protecting essential needs and addressing urgent payment problems. A missed housing payment or interruption in essential services can have consequences that are more immediate than credit card interest.

    If you can’t afford your credit card minimum, contact the issuer as soon as possible. You may be able to discuss a hardship arrangement or other payment options. This isn’t the time to follow a rigid savings percentage or debt payoff formula.

    A Simple Way to Decide What to Do With Your Next $100

    1. Am I current on my essential bills and required debt payments? If not, start there.
    2. Do I have enough cash to handle a small emergency? If not, consider building a starter cushion.
    3. Am I paying a high interest rate on debt? If so, reducing that balance can save money.
    4. Would paying down debt leave me without cash for something I know is coming? If so, make room for that expense first.

    You don’t have to make a perfect decision with every dollar. You need a decision that makes your next month a little more manageable.

    What Happens After I Pay Off My High-Interest Debt?

    Once you’ve reduced or eliminated expensive debt, you may be able to put more money toward a larger emergency fund.

    A commonly suggested long-term goal is three to six months of essential living expenses, although the right amount depends on your circumstances. If essential expenses are $2,500 per month, that means $7,500 to $15,000.

    You might start with $500, build toward $1,000, then work toward one month of expenses. From there, keep increasing your cushion as your budget allows.

    And don’t forget expenses you know are coming. Annual insurance premiums, car maintenance, and holiday spending aren’t really emergencies. Setting money aside for them separately helps protect your emergency fund.

    So, Should You Save or Pay Off Debt?

    If you have no emergency savings, building a small cash cushion may be a sensible first step. If you already have enough cash for a small emergency and you’re carrying high-interest debt, directing extra money toward that debt may be the better next move.

    If your income is uncertain, you may need a larger cushion. And if you’re struggling with essential bills, those needs come first.

    You don’t have to choose between being responsible with your debt and protecting yourself from emergencies. You can work toward both, even if you have to do it a little at a time.

    The important thing is to know what your money needs to do next. And once you’ve made that decision, you can stop second-guessing every dollar and start building a little more breathing room.

    Keep Talking With Emma

    If you’re working through debt, savings, or a budget that never seems to leave enough money, these resources can help:

    Explore the Talkin With Emma books on money, budgeting, and credit, or sign up for Emma’s Mailbox on our homepage for more everyday answers.

    Friendly conversations. Practical tools. Clear explanations.

    This article is for general educational purposes and is not individualized financial advice.
    Share This Conversation
  • Does Paying Off a Credit Card Improve Your Credit Score Immediately?

    Does Paying Off a Credit Card Improve Your Credit Score Immediately?

    Short answer: Paying off a credit card can help your credit score, especially if it lowers your credit utilization. But the improvement usually isn’t immediate, and it isn’t guaranteed. Your card issuer generally has to report the updated balance before a credit scoring model can use it.

    Imagine you just made the last payment on a credit card. You open your credit monitoring app the next morning, expecting a celebration. Instead, your score hasn’t moved.

    That can be frustrating. But it doesn’t necessarily mean your payment made no difference. Let’s look at what happens between paying the card and seeing a possible score change.

    Why Doesn’t My Credit Score Change Right Away?

    Your credit card company knows about your payment when it posts to your account. The credit bureaus may not know yet.

    Many card issuers send updated account information to the credit bureaus about once a month, often around the statement closing date. The exact timing varies by issuer, and the bureaus and credit monitoring services may update on different schedules.

    So your account might show a zero balance while your credit report still shows last month’s balance. A score calculated from that older report won’t reflect the payment yet.

    How Can Paying Off a Card Help Your Score?

    One important factor in many credit scoring models is credit utilization: how much of your available revolving credit you’re using.

    For example, if your card has a $2,000 limit and a $1,000 reported balance, you’re using 50% of that card’s limit. If the reported balance drops to $200, you’re using 10%. If it drops to zero, you’re using none of that card’s limit.

    That lower reported balance may help your score. But scoring models also consider payment history, other debts, account age, recent applications, and the rest of your credit report. There’s no universal number of points you’ll gain from paying off a card.

    How Long After Paying Off a Credit Card Will My Score Update?

    Often, the updated balance appears after the issuer’s next reporting cycle. That may take several weeks, depending on when you paid and when your card reports. Your credit monitoring app may take additional time to display a new score.

    Here’s the distinction I want you to remember: your payment date, your statement date, your credit-report update, and your score refresh are not necessarily the same date.

    If those dates are confusing, I explain them in Should I Pay My Credit Card Before the Statement Date or the Due Date?

    What If My Score Doesn’t Go Up?

    First, check whether the new balance has actually been reported. If it hasn’t, give the normal reporting cycle time to finish.

    If the lower balance is showing and your score still hasn’t increased, remember that different scoring models weigh information differently. Another change on your credit report may also be affecting the result. A credit score is a snapshot of the information available to that particular model at that moment.

    Also, don’t confuse a paid-off card with a card that was closed. Those are separate events, and closing a card can change the amount of available credit used in utilization calculations.

    Should I Close the Card Once It’s Paid Off?

    Not automatically. Keeping an account open may preserve available credit, which can be useful for utilization. But there may be practical reasons to close a card, such as an annual fee or difficulty managing the account. Consider the full picture rather than assuming that paid off means it should be closed.

    What Should I Do After Paying Off My Credit Card?

    1. Confirm that the payment posted and the account balance is what you expected.
    2. Check your next statement and allow time for the issuer’s usual credit reporting cycle.
    3. Review your credit reports for the updated balance. You can access free reports through AnnualCreditReport.com.
    4. If a balance remains incorrect after the normal reporting period, contact the issuer and consider disputing inaccurate credit-report information.
    5. Keep paying other bills on time. One card balance is only part of your credit picture.

    A Final Word From Emma

    Paying off a credit card is meaningful progress, even when a number on your screen doesn’t change the next morning. You’ve reduced a debt, and if that debt was charging interest, you’ve also reduced or eliminated that interest cost going forward.

    Give the reporting process time, check the facts, and don’t let a delayed score update take away from what you’ve accomplished.

    Keep the Conversation Going

    Want to understand more about the timing? Read Should I Pay My Credit Card Before the Statement Date or the Due Date?. You can also explore more practical money and credit topics at Talkin With Emma.

    This article provides general educational information, not individualized financial advice. Credit scoring results vary by model and individual credit history.
    Share This Conversation
  • If You Couldn’t Handle the Bills for 30 Days, Would Someone Else Know What to Do?

    If You Couldn’t Handle the Bills for 30 Days, Would Someone Else Know What to Do?

    Most of us have some kind of system for paying the bills.

    It may be a very organized system with a spreadsheet, calendar, and automatic payments.

    It may be a stack of envelopes on the counter.

    Or it may be a system that mostly lives in your head.

    You know the electric bill comes out around the 12th. You know which credit card pays for the streaming services. You know the car insurance is automatic, but the water bill isn’t. You know which bill sometimes changes and which account needs a little extra money before payday.

    That can work perfectly well—until you’re suddenly not available to handle it.

    What would happen if you couldn’t take care of the household finances for the next 30 days?

    Not forever.

    Just a month.

    Maybe you’re in the hospital. Maybe you have to leave town unexpectedly to help a family member. Maybe you’re sick enough that keeping track of due dates is the last thing you want to think about.

    Would someone else know what needs to be done?

    The Problem Isn’t Always the Money

    When we talk about preparing for emergencies, we tend to think about having enough money.

    That’s important, but there’s another problem that gets much less attention:

    Does anyone else know how your household actually works?

    You can have plenty of money sitting in the bank and still end up with a late payment if nobody knows a bill needs to be paid.

    You can have automatic payments set up and still have trouble if nobody knows which account they’re coming from.

    You can have excellent insurance and still miss a premium notice because you’re the only person who checks that email account.

    A household develops dozens of little routines like these.

    Usually, we don’t notice how much information we’re carrying around until someone else has to take over.

    Start With the Bills That Keep the Household Running

    You don’t need to document every purchase you’ve ever made.

    Start with the things that would cause a real problem if nobody handled them for a month.

    • Mortgage or rent
    • Electricity
    • Water
    • Gas
    • Internet and phone service
    • Insurance premiums
    • Car payments
    • Credit cards
    • Loan payments
    • Childcare
    • Regular medical expenses
    • Pet expenses
    • Important subscriptions or services

    Your list will probably look different from someone else’s. That’s fine.

    The goal isn’t to create the perfect household-finance binder. The goal is to make sure another person could look at your information and understand what needs attention.

    Write Down How Each Bill Is Paid

    Next to each bill, write down a few basic details.

    When is it normally due?

    You don’t necessarily need the exact date if it changes. “Middle of the month” may be enough to remind someone to check.

    Is it paid automatically?

    This matters because an automatic payment doesn’t mean a bill can be ignored. Someone still needs to make sure there’s enough money in the account.

    Where is the bill normally found?

    Does it arrive by mail? Email? An app? Does someone have to log into an online account to see it?

    That little piece of information can save someone a surprising amount of detective work.

    Don’t Put Sensitive Information on the List

    There’s an important difference between making a useful household guide and creating a piece of paper containing everything someone would need to steal your identity.

    Your basic bill list doesn’t need to include full bank account numbers, credit card numbers, Social Security numbers, PINs, or passwords.

    Instead, the list might say:

    Electric company — automatic payment — checking account — around the 14th

    or

    Car insurance — paid manually — bill comes by email — due near the end of the month

    That’s enough to tell someone what exists and where to start.

    Sensitive information should be stored separately and securely.

    Check Your Automatic Payments

    Automatic payments make life easier, but they’re worth reviewing as part of this exercise.

    Ask yourself: If I didn’t touch my finances for 30 days, would there be enough money in the account to cover everything scheduled to come out?

    This is especially important if you normally move money between accounts throughout the month.

    For example, maybe your mortgage, insurance, and utilities all come from checking, but you normally transfer money into that account every payday.

    Someone looking at your bank balance might assume everything is handled because the bills are automatic.

    It isn’t if the money that normally funds those payments never gets moved.

    Write down the routine, not just the bill.

    Think About the Things That Aren’t Bills

    Some household responsibilities don’t arrive with a due date.

    Maybe someone needs to refill a prescription. Maybe the dog gets medication every month. Maybe you regularly order supplies for an older family member. Maybe a child has an activity that requires a monthly payment. Maybe the propane tank needs to be watched. Maybe there’s a service you have to schedule rather than simply pay.

    Ask yourself: What do I routinely remember so nobody else has to?

    Those are exactly the things another person may not know about.

    Decide Who Should Know This Information Exists

    Creating the list doesn’t help very much if nobody knows where it is.

    You don’t necessarily need to hand copies to several people.

    You do need at least one trusted person who knows something like: “If something happens and I can’t handle things for a while, here’s where I keep the household information.”

    Depending on your situation, that might be your spouse or partner, an adult child, a parent, a sibling, or another person you trust.

    The right person is going to be different for every household.

    Try the 30-Minute Test

    You don’t need to turn this into an all-day project.

    Set aside about 30 minutes and see how much you can identify.

    • Your recurring household bills
    • Approximately when they’re due
    • Which ones are automatic
    • Where the bills or notices arrive
    • Which account normally pays them
    • Regular responsibilities that aren’t traditional bills
    • Where important household information is stored
    • Who should know this list exists

    Then look at it from the perspective of someone who doesn’t normally handle your finances.

    Would they know what to do next?

    If not, add the missing explanation.

    This Isn’t About Planning for the Worst

    You don’t need to imagine some terrible disaster to make this useful.

    Sometimes life is simply inconvenient.

    People get sick. Family emergencies happen. Trips get extended. Phones break. Passwords get forgotten.

    The person who normally handles everything occasionally needs someone else to take over.

    A little organization now can make that much easier.

    And there’s another benefit.

    Once you put everything in one place, you may discover things about your own finances that you’ve stopped noticing.

    A subscription you don’t use. A bill that would be easier on autopay. An automatic payment coming from the wrong account. A service you forgot you were paying for. Or simply a household system that makes much more sense in your head than it does on paper.

    That’s useful information even if nobody else ever has to use your list.

    One Small Step This Week

    You don’t have to build an emergency binder today.

    Start smaller.

    Make the recurring-bill list.

    That’s it.

    Once you’ve done that, you have something you can improve over time instead of a project you’ve been meaning to start someday.

    And if you’re thinking more broadly about what your household would need when normal routines get interrupted, Let’s Talk About Emergencies walks through practical ways to prepare before you’re dealing with the emergency itself.

    Friendly conversations. Practical tools. Clear explanations.

    — Emma

    Want a Little More Help?

    If this has you thinking about how your household money is organized, you do not have to rebuild your whole system today. Start with one useful next step.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • Should I Pay My Credit Card Before the Statement Date or the Due Date?

    Should I Pay My Credit Card Before the Statement Date or the Due Date?

    If you have ever tried to figure out the “right” day to pay a credit card, the internet can make a simple bill feel like a strategy game.

    Pay before the statement date. Pay on the due date. Pay twice a month. Leave a tiny balance. Never leave a balance.

    That is a lot of rules for something that should be much easier.

    Here is the short answer: If your goal is to make an on-time payment and, when your card has an applicable grace period, avoid interest on purchases, focus on paying the amount required by your card agreement by the due date. If you are trying to lower the balance that may appear on your credit reports, making a payment before the statement closes may help because many issuers report account information around the end of a billing cycle. You do not need to carry a balance or pay interest to build credit.

    First, What Is the Statement Date?

    Your credit card runs on billing cycles. At the end of a cycle, the card company creates a statement showing what happened during that period.

    That statement usually includes your statement balance, minimum payment, payment due date, interest and fees, credit limit, and a list of transactions.

    Think of the statement closing date as the point when the card company takes a snapshot of that billing cycle and prepares your bill.

    Then What Is the Due Date?

    The due date is the deadline for the payment shown on your statement.

    At minimum, you need to make the required minimum payment by the due date to keep the payment from being late. Federal rules generally require card issuers to deliver or mail statements at least 21 days before the payment is due.

    If your card provides a grace period on purchases and you meet its terms, paying the applicable statement balance in full by the due date can generally let you avoid interest on those purchases. Check your own card agreement because grace periods are not required and their terms can differ.

    So Why Would Anyone Pay Before the Statement Closes?

    This is where credit utilization enters the conversation.

    Credit utilization is basically how much of your available revolving credit you are using. If you have a $1,000 limit and a $500 reported balance, that card is showing 50% utilization.

    Credit scoring models can consider utilization. The balance that appears on a credit report is not necessarily the balance sitting in your account on the exact day someone checks your credit. Credit card companies periodically report account information to the credit bureaus, and the timing can vary by issuer.

    That means a person who pays a card in full every month can still have a balance reported.

    For example, imagine you have a $1,000 limit. You spend $600 during the month. Your statement closes showing $600, and then you pay that $600 in full before the due date.

    You did not do anything wrong. You paid your bill as agreed. But if the issuer reported the $600 balance, your credit report may temporarily show relatively high utilization on that card.

    If you had paid $400 before the statement closed, the statement might instead close with $200, depending on when the payment posted and when the issuer reports. That could mean a lower reported balance.

    That is the practical reason some people make an early payment. It is not because paying on the due date is automatically bad.

    Do I Need to Leave a Balance to Build Credit?

    No.

    This is one of those credit myths that refuses to go away.

    You do not need to carry debt from one billing cycle to the next and pay interest just to prove that you can use credit. On-time account history can help build credit without deliberately paying interest.

    If you can pay your statement balance in full and your card’s grace-period terms apply, paying it by the due date is usually the less expensive approach.

    What Is the Difference Between the Minimum Payment and the Statement Balance?

    This distinction matters much more than memorizing a special payment trick.

    The minimum payment is the smallest amount your issuer says you must pay by the due date to satisfy that month’s required payment.

    The statement balance is the balance shown when that billing cycle closed.

    If you pay only the minimum, the rest does not disappear. You may pay interest on the unpaid amount, and paying a debt down can take much longer.

    If money is tight and you cannot pay the full statement balance, do not let “I can’t pay it all” turn into “so I won’t pay anything.” Making at least the required minimum payment on time is important. Then look at what you can realistically pay above it.

    Is It Bad to Pay My Credit Card More Than Once a Month?

    No. You can generally make more than one payment during a billing cycle.

    For some people, that is useful. Maybe you get paid every two weeks and prefer paying part of the card each payday. Maybe making an early payment helps keep your reported balance lower. Maybe smaller payments simply make the household budget easier to manage.

    Those are practical reasons.

    What you do not need is a complicated schedule because someone online promised that paying on two magic days will automatically boost your score.

    Please Don’t Turn This Into Another Credit-Score Game

    Once people learn that reported balances can affect utilization, it is easy to start micromanaging every purchase and payment.

    You probably do not need to do that.

    Credit scores can matter, especially when you are preparing to apply for a mortgage, auto loan, apartment, or another product where your credit will be reviewed. In that situation, paying balances down before they are reported may be useful if utilization is high.

    But for everyday credit management, the bigger habits are much less exciting:

    • Know your due date.
    • Make at least the required payment on time.
    • Pay the statement balance in full when you reasonably can and when that fits your card’s terms.
    • Keep an eye on how much of your available credit you are using.
    • Read your statements.
    • Do not spend money just because credit is available.

    Those habits are not flashy enough for a viral “credit hack,” but they are much more useful.

    A Simple Credit Card Routine

    If you want to keep this simple, try this:

    1. Check your statement every month. Make sure the transactions look right and note the statement balance, minimum payment, and due date.
    2. Set up a reminder or autopay. At the very least, protect yourself from accidentally missing the required payment.
    3. Pay the statement balance in full when you can. If your card has an applicable grace period and you meet its conditions, this can help you avoid purchase interest.
    4. If your reported balance is high, consider paying earlier. An extra payment before the statement closes may reduce the balance that gets reported, depending on your issuer’s reporting schedule.
    5. If you cannot pay in full, make a plan instead of avoiding the bill. Pay at least the required minimum on time, then decide how much extra you can put toward the balance.

    That is enough. You do not need to turn paying a credit card into a part-time job.

    Quick Questions

    Does paying before the statement date help my credit score?

    It can help lower the balance that may be reported to the credit bureaus, which may lower your reported utilization. Whether that changes a particular score depends on the information in your credit report and the scoring model being used.

    When do credit card companies report balances?

    Reporting schedules vary. Many issuers report periodically around the end of a billing cycle, but you should not assume every issuer reports on the same day. You can check your credit reports to see what balance is appearing and ask your issuer about its reporting practices.

    Should I leave a small balance on my card?

    You do not need to carry a balance from month to month or pay interest in order to build credit.

    Should I pay on the statement date or due date?

    You do not have to wait for either date to make a payment. The due date is the important deadline for making the required payment on time. Paying earlier can be useful for budgeting or for reducing the balance that may be reported.

    What if I cannot afford the statement balance?

    Pay at least the required minimum by the due date if you can, then pay as much additional principal as your budget reasonably allows. If you are struggling to make even the minimum payment, contact the card issuer as soon as possible rather than waiting until after you miss it.

    The Bottom Line

    The statement date and the due date do two different jobs.

    The statement date closes out a billing cycle and helps determine what appears on that month’s statement. The due date tells you when the required payment must be received.

    If you want the simplest rule, start here: pay on time, pay the statement balance in full when you reasonably can, and do not carry debt just because someone told you it helps your credit.

    Once you understand what the dates and numbers actually mean, credit gets a lot less mysterious.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If you’re trying to make credit-card payments fit more comfortably into the rest of your month, it can help to look at the whole money picture instead of one due date at a time.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • Why Does My Bank Account Say I Have Money When I’m Still Broke?

    Why Does My Bank Account Say I Have Money When I’m Still Broke?

    You check your bank account and see $600.

    For about three seconds, that feels pretty good.

    Then you remember the electric bill comes out tomorrow.

    Car insurance is due Friday.

    You bought groceries yesterday, but that charge is still sitting there as pending.

    And at least some of that money needs to stay right where it is because rent is coming.

    So, yes. There is $600 in your account.

    That does not mean you have $600 to spend.

    This is one of those money problems that gets much easier once somebody explains what is actually happening. Your bank balance is giving you useful information. It just is not giving you the whole picture.

    Let’s sort out the rest of it.

    What Does My Bank Balance Actually Tell Me?

    Your bank balance tells you how much money is in the account according to the transactions your bank has processed.

    That’s important.

    But your bank does not know your plan.

    It does not know that you need $150 of that money for the electric bill.

    It does not know that you need enough gas to get through next week.

    It definitely does not know that the $100 sitting there is the beginning of the money you are setting aside for your car registration.

    You know those things.

    That’s why I don’t want you making spending decisions based only on the big number at the top of your banking app.

    That number answers:

    How much money is in my account?

    What we really need to know is:

    How much of that money is actually available for me to spend?

    Those are not always the same number.

    What Is the Difference Between My Current Balance and Available Balance?

    Your banking app may show you a current balance and an available balance.

    They sound like they should make everything perfectly clear.

    Naturally, they do not.

    Your current balance generally reflects the transactions that have already posted to your account.

    Your available balance usually does a little more work for you. It may account for pending transactions or holds the bank already knows about.

    So if you spent $60 at the grocery store this morning and that transaction is still pending, your available balance may give you a better picture of what is actually left.

    That’s helpful.

    But there is still a problem.

    Your bank only knows about the things your bank knows about.

    If your $175 utility bill is due Thursday but has not been paid yet, your bank cannot reserve that $175 for you.

    If you need $80 for groceries until payday, your bank does not set that aside.

    If your car registration is due next month, your banking app is not going to tap you on the shoulder and say, “Emma, maybe leave some of this alone.”

    That’s your part of the job.

    Why Can I Have Money in the Bank and Still Be Broke?

    Because some of that money may already belong to something else.

    Let’s say you have $600 available right now.

    Before you get paid again, you need:

    • $175 for utilities
    • $125 for car insurance
    • $100 for groceries
    • $60 for gas
    • $75 for another bill

    That’s $535.

    You still have $600 in the bank.

    But $535 already has somewhere to go.

    That leaves $65 that is not already committed.

    Now imagine looking at that $600 balance and deciding a $100 purchase is fine because you have plenty of money in the account.

    You do have enough to make the purchase.

    You just don’t have enough to make the purchase and do everything else that money needs to do.

    That’s the part that gets us.

    The purchase works today.

    The problem shows up Friday.

    How Do I Know How Much Money I Can Actually Spend?

    We can make this pretty simple.

    Start with the money you have available.

    Then subtract the money you need before more income comes in.

    Money available now − money already needed = money that is not committed

    Let’s try it.

    You have $900.

    Before your next paycheck, you need:

    • $500 for bills
    • $150 for groceries and gas
    • $100 for an expense you already know is coming

    So:

    $900 − $500 − $150 − $100 = $150

    That $150 is much more useful to me than the $900 at the top of the banking app.

    I think of it as safe-to-spend money.

    It is the money left after we have accounted for the things that need to happen first.

    Does that mean you need to immediately spend the whole $150?

    Of course not.

    It means you now know what you’re actually working with.

    And knowing is a lot easier to work with than hoping.

    Don’t Forget the Expenses That Don’t Happen Every Month

    Monthly bills usually aren’t the hardest ones to remember.

    Rent has a way of reminding us it exists.

    So does the electric company.

    It’s the other expenses that like to disappear for a while and then wander back into our lives asking for $300.

    Car registration.

    School expenses.

    Annual memberships.

    Holiday spending.

    Vet visits.

    Insurance premiums.

    Birthdays.

    Home repairs.

    Car maintenance.

    Medical copays.

    None of these is necessarily unexpected.

    We just don’t pay them every month, so they’re easy to leave out when we’re thinking about what our money needs to do.

    If this keeps happening to you, I talked more about why a budget can fail even when the math works.

    One simple thing you can do is start turning those larger future expenses into smaller current ones.

    Suppose you know you’ll need $300 six months from now.

    Finding $300 all at once might hurt.

    Setting aside $50 a month for six months may be much easier.

    Same $300.

    Much less drama.

    What If I Use Cash Instead of a Banking App?

    Good.

    This still works.

    You do not need an app, spreadsheet, online bank account, or fancy budgeting system to know what your money needs to do.

    If you use cash, envelopes can actually make this idea very easy to see.

    Maybe you have:

    • $200 in the rent envelope
    • $100 in groceries
    • $60 in gas
    • $75 in utilities
    • $50 in savings
    • $40 in spending money

    Altogether, you have $525.

    But you wouldn’t dump all six envelopes onto the table, count the money, and decide you have $525 available for dinner and shopping.

    The labels matter.

    Your rent money is still rent money.

    Your gas money is still gas money.

    And your $40 of spending money is the part you can spend without stealing from something else.

    A budget is doing the same job.

    You can keep yours on paper, in envelopes, on your phone, in a spreadsheet, or wherever it makes sense to you.

    I care much more about whether you know what the money is supposed to do than where you write it down.

    What If My Safe-to-Spend Number Is Negative?

    Let’s say you do the math and get this:

    Money available: $700

    Money you need before payday: $850

    Difference: -$150

    Well, that’s not the answer we were hoping for.

    But I would much rather you know about that $150 shortage now than discover it three days before payday.

    A negative number is information.

    It tells us we have a problem to solve.

    Now we can ask useful questions.

    What absolutely has to be paid before payday?

    What can wait?

    Is there a bill due date that can be moved?

    Is there an expense we can reduce this time?

    Is this a one-time problem, or are we coming up short by roughly the same amount every month?

    That last question matters.

    If this happens once because three unusual expenses landed in the same week, we solve this week.

    If you’re $150 short every single month, we have a bigger problem to work on.

    Neither problem gets easier by refusing to look at the number.

    Finding it early gives you time to make decisions.

    Do I Need a Complicated Budget to Do This?

    No.

    And I really don’t want you building a complicated budget just because somebody told you a “real” budget needs 47 categories and a color-coded spreadsheet.

    If you love spreadsheets, wonderful.

    Use one.

    If you would rather use a notebook and a pen, use those.

    If cash envelopes make sense to your brain, get the envelopes.

    Your budget needs to help you answer a few questions:

    What money is coming in?

    What needs to be paid?

    When does it need to be paid?

    What expenses do I know are coming later?

    What can I safely spend after I account for those things?

    If your system can answer those questions, we have something useful.

    We can make it prettier later.

    Your Bank Balance Needs Context

    I don’t want you to stop checking your bank balance.

    Please check it.

    We just aren’t going to ask that one number to do a job it cannot do.

    If your account says $600, then yes, you have $600 in the account.

    But your budget may tell you:

    $175 is for utilities.

    $125 is for insurance.

    $100 is for groceries.

    $60 is for gas.

    $75 is for another bill.

    And $65 is left.

    Now that $600 means something.

    That’s the difference.

    Instead of looking at your account and asking:

    “Do I have money?”

    Try asking:

    “What does this money need to do before I get paid again?”

    That question will tell you a lot more.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If your bank balance keeps giving you the wrong impression, a simple check-in can help you give the money in your account a job before you decide what is safe to spend.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want to go a little deeper?
    Take a look at Let’s Talk About Budgeting.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • Why Your Budget Keeps Failing Even When the Math Works

    Why Your Budget Keeps Failing Even When the Math Works

    You sit down, add everything up, give every dollar somewhere to go, and the numbers work.

    Then real life gets involved.

    A bill shows up that you forgot about. Groceries cost more than you planned. You pull cash from an envelope and forget what it was for. Three subscriptions renew in the same week. By the middle of the month, the budget that looked perfectly reasonable on paper is already wobbling.

    That does not automatically mean you need more discipline. Sometimes the math is fine. The problem is that the budget is not describing your real life closely enough.

    Before you throw it away and start over, let’s figure out what actually broke.

    1. Your budget may be missing real expenses

    Monthly bills are easy to remember because they keep showing up. The expenses that happen every few months—or once a year—are easier to forget.

    Car registration. School costs. Gifts. Annual subscriptions. Vet visits. Holiday spending. A yearly membership. Replacing worn-out shoes. The repair you know the car will eventually need.

    None of those expenses becomes an emergency just because it did not happen last month.

    Look back through the last year if you can. What expenses showed up that were not part of an ordinary month? Divide annual costs by 12, or start setting aside whatever amount you realistically can. The goal is not mathematical perfection. The goal is to stop being surprised by expenses you already know are coming.

    2. The problem may be timing, not spending

    Here is one that trips people up: your monthly income can cover your monthly expenses and you can still run short of money.

    Why?

    Because bills do not care what your monthly total looks like.

    If most of your bills are due during the first week of the month but your income arrives throughout the month, you can have enough money overall and still have a miserable first week.

    That is a cash-flow problem.

    Put your paydays and due dates on the same calendar. If one stretch is overloaded, see whether a company will move a due date. You can also gradually build a small buffer so this paycheck is not responsible for every bill that arrives before the next one.

    Sometimes the budget does not need a cut. It needs better timing.

    3. Cash still counts

    You do not need digital accounts, budgeting software, or an app to have a working budget.

    If you prefer cash, an envelope system can work perfectly well. The important part is knowing what the cash is supposed to do.

    You might have envelopes for groceries, gas, household expenses, fun money, or anything else that makes sense for you. When you spend from an envelope, you do not need to record every purchase in an app unless that helps you. You can simply subtract the amount, keep the receipt in the envelope, or write the purchase on the back of the envelope.

    The envelope itself can be the record.

    What causes trouble is pulling $40 from one envelope, spending $18, putting the change in your pocket, and eventually having no idea which category that money belonged to.

    Cash is not outside the budget. It is simply another place your budget lives.

    4. Your numbers may be too optimistic

    This is one of the easiest budgeting mistakes to make because it feels productive.

    You normally spend $700 on groceries, so you write $450 in the new budget.

    Great. You just saved $250.

    Except you did not.

    You changed a number on paper.

    If you want to lower a category, start with what you actually spend and decide what will make the lower number possible. Maybe you change where you shop, plan more meals, reduce takeout, use what is already in the freezer, or lower the category gradually.

    A goal can stretch you a little. It should not require an entirely different person to live your life.

    5. Your budget may only be paying obligations

    Before deciding what every category should look like, ask one more question:

    What do you want this budget to make easier?

    Maybe you want fewer late fees and less panic between paydays. Maybe you want room for time with friends, a gym membership you actually use, travel, a class, or a goal you have been putting off. Maybe you simply want annual bills to stop feeling like emergencies.

    A budget works better when it is helping you move toward something—not only telling you what to stop doing.

    Write down one or two things you want your money plan to support. Those priorities matter when you decide what to keep, cut, and redirect.

    There is nothing wrong with having a fun category. There is nothing irresponsible about planning for something you enjoy.

    The point of managing money is not to become exceptionally good at paying bills until you die.

    It is to make your money support your actual life.

    6. Find what broke before you start over

    When a budget stops working, it is tempting to delete everything, make a prettier spreadsheet, choose new category amounts, and declare Monday the beginning of a new financial era.

    Before you do that, ask what happened to the last one.

    Was an expense missing?

    Were the numbers unrealistic?

    Did the timing of your bills cause trouble?

    Did cash spending disappear from the plan?

    Were there so many categories that keeping up with them became a second job?

    Did you build a budget for the month you wished you had instead of the month you actually have?

    You do not need to diagnose yourself as “bad at budgeting.” You need to identify the part of the system that failed.

    Systems can be changed.

    Try this today

    Find the last budget or money plan that did not work and finish this sentence:

    My budget became difficult to follow when ____________________.

    Do not fix it yet.

    Name the problem first.

    Then ask what one change would make that specific problem less likely next month.

    Maybe you need to add an annual-expenses category. Maybe you need to move a due date. Maybe groceries need a realistic number. Maybe your cash envelopes need a simple way to track what leaves them.

    One useful correction is better than rebuilding the entire budget because you think you failed.

    A better budget should make life clearer

    Your budget does not have to be impressive.

    It does not need 40 categories, a complicated spreadsheet, or an app that sends you notifications every time you buy toothpaste.

    It needs to tell you the truth about the money coming in, the money going out, the things that do not happen every month, and the things you want your money to help you do.

    If the math works but the budget keeps failing, look beyond the math.

    The problem may be sitting somewhere else entirely.

    Want a Little More Help?

    If your budget keeps breaking in real life, start by looking at what actually happened this month instead of immediately building another perfect plan.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want to go a little deeper?
    Take a look at Let’s Talk About Budgeting.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • 7 Small Household Habits That Can Save You Money Over Time

    7 Small Household Habits That Can Save You Money Over Time

    Saving money at home does not always mean making a big change.

    Sometimes it is the small things you do over and over that make the biggest difference.

    A few dollars here and there may not feel important in the moment. But when the same small savings happen every week or every month, they can add up.

    Here are seven household habits that can help you spend a little less without turning your life upside down.

    1. Check Recurring Charges Once a Month

    Subscriptions are easy to forget because they happen automatically.

    Once a month, take a few minutes to look at the recurring charges coming out of your bank account or credit card.

    Ask yourself:

    • Do I still use this?
    • Has the price changed?
    • Am I paying for two services that do almost the same thing?
    • Is there a cheaper plan that would work just as well?

    You do not have to cancel everything. The goal is simply to notice what you are paying for.

    2. Make a Short Grocery List Before You Shop

    You do not need a complicated meal plan to save money on groceries.

    A short list can help.

    Before you leave for the store, look through the refrigerator, freezer, and pantry. Then write down what you actually need.

    This can help prevent buying duplicates, forgetting ingredients, and making extra trips later in the week.

    It also makes it easier to use food you already have before it goes bad.

    3. Use Appliances in Full Loads When You Can

    Running the dishwasher or washing machine for only a few items can use nearly as much water and energy as a fuller load.

    You do not need to pack appliances so tightly that they stop working properly. Just try to avoid running them half-empty when waiting a little longer would be easy.

    It is a small habit, but over time it can mean fewer cycles and less wasted water and electricity.

    4. Give the Thermostat a Little Attention

    Heating and cooling can be a large part of a household utility bill.

    You do not need to make your home uncomfortable to save money.

    Instead, pay attention to small changes. A slightly different thermostat setting when you are asleep or away may help reduce energy use.

    Also check simple things that affect how hard the system has to work, such as:

    • dirty air filters,
    • doors or windows left open,
    • sunlight heating a room you are trying to cool, and
    • vents blocked by furniture.

    Little adjustments can matter when they happen every day.

    5. Maintain Things Before They Break

    Routine maintenance is not exciting, but repairs are usually even less exciting.

    Changing filters, cleaning dryer vents, checking appliance hoses, keeping gutters clear, and following basic maintenance schedules can help household equipment last longer.

    Not every breakdown can be prevented. But taking care of what you own can reduce avoidable problems and help you notice trouble earlier.

    A small maintenance cost today may be much easier to handle than a major repair later.

    6. Review Bills and Renewals Instead of Letting Them Roll Over

    It is easy to let insurance, internet, phone service, and other household bills renew without looking at them.

    Before a renewal or contract change, take a few minutes to check:

    • what you are paying now,
    • whether the price increased,
    • whether you still need all the features or coverage included, and
    • whether another option is worth comparing.

    You do not need to switch companies every year. Sometimes the current option is still the best one.

    The useful habit is checking instead of assuming.

    7. Do a 10-Minute Weekly Money Check

    A weekly money check does not have to be a full budgeting session.

    Set aside about 10 minutes and look at what is coming up.

    You might check:

    • your current account balance,
    • bills due in the next week,
    • automatic payments,
    • any unusual charges, and
    • whether you need to move money before something is due.

    This habit can make money feel less surprising.

    It is often easier to deal with a small issue when you notice it early rather than after a payment is missed or an account is overdrawn.

    Small Habits Work Because They Repeat

    None of these habits will magically cut your household expenses in half.

    That is not really the point.

    The goal is to make a few useful choices often enough that they start working in the background.

    Check what you are paying for. Use what you already have. Take care of the things you own. Give upcoming bills a quick look.

    You do not need to do everything perfectly.

    A small habit that you actually keep is usually more useful than a perfect money plan that lasts for three days.

    — Emma

    Want a Little More Help?

    Small money habits work best when you can see what is changing from month to month. A simple check-in can help you notice what is working and what needs attention next.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • How to Lower Your Monthly Bills Without Making Yourself Miserable

    How to Lower Your Monthly Bills Without Making Yourself Miserable

    You need to spend less.

    Okay.

    So you start looking around.

    Cancel Netflix.

    Stop buying coffee.

    Never eat at a restaurant again.

    Apparently happiness has been removed from the budget.

    And after all that?

    You saved $31.

    This is my problem with a lot of advice about cutting expenses.

    Yes, little things add up.

    But so do big things.

    And if we’re trying to create some actual breathing room in your budget, I’d rather look for $50 in one place before chasing $2 in twenty-five places.

    So let’s go looking for the bigger stuff first.

    Start With the Bills That Come Back Every Month

    Recurring expenses are a good place to start because you usually only have to make the change once.

    Save $30 on something you buy one time?

    You saved $30.

    Lower a recurring bill by $30 a month?

    That’s $360 over a year if the savings continues.

    Much more interesting.

    Pull up your bank or credit card statements and look for the bills that keep coming back.

    Phone.

    Internet.

    Insurance.

    Subscriptions.

    Memberships.

    Software.

    Storage.

    Anything else you’re paying repeatedly.

    We’re not cancelling everything.

    We’re asking whether you’re still getting enough value for what you’re paying.

    Start With the Biggest Bills You Can Actually Change

    Your mortgage might be your biggest bill.

    That doesn’t mean you’re going to solve it this afternoon.

    We’re looking for expenses that are both:

    Big enough to matter.

    and

    Realistically changeable.

    Your phone bill might qualify.

    Internet might.

    Insurance might.

    A collection of subscriptions might.

    A service plan you signed up for four years ago and haven’t looked at since definitely deserves an invitation to this conversation.

    Start there.

    Call the Phone Company

    I know.

    Nobody woke up this morning hoping to spend part of the day talking to the phone company.

    Do it anyway.

    Look at your current plan.

    How much are you paying?

    What are you actually getting?

    Are you financing devices?

    Paying for insurance or add-ons?

    Using all the lines?

    Then look at what’s available now.

    Your provider may have a less expensive plan that still works for you. Another provider might too.

    Sometimes simply asking:

    “Are there any less expensive plans available that would still meet my needs?”

    can turn up an option you didn’t know existed.

    Don’t assume the plan you’ve had for five years is still the best deal.

    Companies change their offers.

    Your needs change too.

    Do the Same Thing With Internet

    Internet bills have a habit of starting at one number and eventually becoming another number entirely.

    Maybe a promotional rate expired.

    Maybe the price increased.

    Maybe you’re paying for speed you don’t need.

    Maybe equipment fees have quietly joined the party.

    Pull up the actual bill—not just the amount coming out of your account.

    What are you paying for?

    Then check what’s currently available.

    If there’s a lower-cost plan that meets your needs, ask about it.

    If a competitor has a better offer, that’s useful information too.

    You don’t necessarily have to switch.

    But knowing your options makes for a much more interesting phone call.

    Shop Your Insurance—Carefully

    Insurance can be another meaningful recurring expense.

    Auto.

    Homeowners.

    Renters.

    Other coverage you may have.

    If you haven’t compared rates in a while, getting quotes can be worth doing.

    But please don’t shop insurance by price alone.

    A quote that’s $40 cheaper isn’t necessarily a better deal if the coverage changed.

    Check:

    Coverage limits
    Deductibles
    Included coverages
    Exclusions or important differences
    Discounts

    Then compare the premium.

    If you want some help keeping those quotes straight, the Insurance Checkup & Quote Comparison Workbook gives you a place to put them side by side.

    A lower insurance bill is wonderful.

    A lower insurance bill because you accidentally removed protection you wanted?

    Less wonderful.

    Now Go Subscription Hunting

    Pull up your statements and find the recurring subscriptions.

    Streaming.

    Music.

    Apps.

    Cloud storage.

    Fitness.

    News.

    Gaming.

    Memberships.

    Software.

    Then ask three questions:

    Do I still use this?

    Would I notice if it disappeared?

    Would I sign up again today at this price?

    That last one catches a lot.

    Maybe you signed up when it was $7.99.

    Now it’s $15.99.

    Would you still buy it?

    If yes, keep it.

    We’re not cancelling things just because they cost money.

    If no?

    There you go.

    Don’t Cancel the Things That Make Your Life Better Just Because They’re Easy Targets

    Your $12 streaming subscription is visible.

    So it’s easy to attack.

    But maybe you use it five nights a week.

    You love it.

    Your family uses it.

    Meanwhile, you’re paying $38 a month for something you haven’t touched since February.

    Which one should go?

    Exactly.

    The goal isn’t to make your bank statement as joyless as possible.

    It’s to stop paying for things that aren’t doing enough for you.

    There’s a difference.

    Look for Fees

    Fees are particularly irritating because they often give you absolutely nothing in return.

    Bank fees.

    Late fees.

    ATM fees.

    Delivery fees.

    Convenience fees.

    Service fees.

    Fees that appear to exist because someone discovered they could charge a fee.

    Look through the last couple of months.

    Are any repeating?

    If you’re regularly paying account fees, see whether another account or institution could reduce them.

    If late fees keep appearing, would changing a due date or setting a reminder help?

    If delivery fees are adding up, maybe you still order food—but pick it up sometimes.

    We’re looking for places where your money is leaving and you’re getting very little in return.

    Check What You’re Paying for Convenience

    Convenience is worth money.

    Time has value too.

    Delivery, prepared food, same-day shipping, and services that save you time aren’t automatically bad.

    The problem is when the cost becomes invisible.

    Let’s say delivery adds $14 to an order.

    Once?

    Fine.

    Twice a week?

    Now we’re talking about roughly $100 or more in some months.

    Maybe that’s worth it to you.

    Great.

    Keep it.

    But make the decision knowing what it costs.

    “I spend about $100 a month on delivery because it makes our busiest nights easier” is a choice.

    “I had no idea we were spending $100 a month on delivery” is a discovery.

    We want choices.

    Look at Groceries Without Declaring War on Food

    Groceries are expensive.

    And advice like:

    “Just spend less at the grocery store”

    isn’t particularly useful.

    You need food.

    Instead of choosing some random amount to cut, look for patterns.

    Food that regularly gets thrown away.

    Multiple little grocery trips that somehow cost $46 every time.

    Impulse purchases.

    Things bought because they’re on sale even though nobody in the house actually likes them.

    That’s where I’d start.

    Reducing food waste by $20 a week is about $80 a month.

    And nobody had to survive on lentils for thirty consecutive days.

    Don’t Ignore Debt Payments

    Debt payments deserve a look too.

    If a big chunk of every paycheck is already spoken for before the month really gets going, write those payments down.

    How much are you paying toward credit cards, personal loans, or other debt every month?

    What are the interest rates?

    Which balances are costing you the most?

    We’re not solving debt in this article.

    That’s its own conversation.

    But eventually, paying off a debt can do more than reduce what you owe.

    It can remove an entire monthly payment.

    That’s when your budget really starts to breathe.

    For now, know the numbers.

    What About the Really Big Expenses?

    Housing.

    Transportation.

    Childcare.

    These can take enormous pieces of a budget.

    They’re also much harder to change.

    I’m not going to tell you:

    “Have you considered simply moving?”

    as though changing homes costs nothing and you can knock it out Tuesday afternoon.

    But if housing or transportation costs keep making the rest of your budget impossible, they may deserve a bigger conversation eventually.

    Some expenses can’t be fixed with one phone call.

    So work on the ones you can change now.

    Keep a Running Total of What You Find

    This is where things start getting satisfying.

    Cancelled unused app:

    $11 a month.

    Changed phone plan:

    $25.

    Reduced internet bill:

    $15.

    Cancelled membership:

    $20.

    Reduced delivery fees:

    $30.

    That’s $101 a month.

    Not life-changing money for everybody.

    But that’s $1,212 over a year if those savings continue.

    And we didn’t ban restaurants.

    Nobody confiscated your coffee.

    You didn’t have to turn the thermostat down to a temperature usually associated with food storage.

    We looked for expenses that weren’t giving you enough back.

    That’s a much more sustainable way to cut spending.

    Now Give the Savings a Job

    This may be the most important part.

    You lowered your bills by $101.

    Fantastic.

    What happens to the $101?

    If you don’t decide, there’s a pretty good chance it simply disappears into regular spending.

    A little more at the grocery store.

    An extra order.

    A couple of random purchases.

    Three months later, you’re wondering why you don’t feel any richer.

    So decide.

    Maybe:

    $40 goes to emergency savings
    $30 goes toward debt
    $20 goes toward an irregular expense
    $11 stays available for something fun

    Your answer can be completely different.

    This is where My Monthly Money Check-In can help.

    Go back through your numbers and replace the old bill amounts with the new ones.

    Then decide where you want the difference to go.

    You didn’t just cut an expense.

    You redirected money.

    That’s the part that actually changes something.

    Don’t Try to Do All of This Today

    Please don’t finish this article and immediately call seven companies.

    Pick one bill.

    Preferably one that could save enough money to be worth the trouble.

    Handle it.

    Then do another next week.

    This isn’t a financial emergency drill.

    We’re gradually making your monthly expenses work better.

    And if you spend twenty minutes on the phone and save $25 a month?

    That’s $300 a year for twenty minutes of annoyance.

    I’ve had worse meetings.

    Cutting Expenses Isn’t About Spending as Little as Possible

    That’s not the goal.

    The goal is having enough room in your budget for the things that matter.

    Bills.

    Food.

    Savings.

    Debt.

    Emergencies.

    And yes…

    Things you enjoy.

    If your budget only works when nothing fun ever happens, I’m not convinced it works.

    Spend intentionally.

    Keep the things that make your life better.

    Question the things that don’t.

    And pay particular attention to the expenses that come back month after month.

    Because a small recurring change can quietly become a pretty decent amount of money over a year.

    Start with one bill.

    See what you can change.

    Then give whatever you save a better job.

    That’s how we create breathing room without making life miserable in the process.

    This article is for general educational and informational purposes only and isn’t intended as individualized financial, investment, tax, or legal advice. Everyone’s financial situation is different. Consider your own circumstances and, when appropriate, consult a qualified financial or other professional before making significant financial decisions.

    Want a Little More Help?

    If you’re trying to create more breathing room in your monthly spending, start by getting a clear picture of what is coming in, what is going out, and what deserves your attention first.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • Why an Emergency Fund Matters Even When You Have Insurance

    Why an Emergency Fund Matters Even When You Have Insurance

    Insurance can protect you from some very expensive problems.

    So if you have insurance, do you really need an emergency fund too?

    Yes.

    Not because your insurance isn’t doing its job. The two simply have different jobs.

    Insurance can help with certain covered losses. An emergency fund gives you money you can reach when life creates an expense right now.

    And sometimes those two things meet in the same afternoon.

    You might have a car accident and discover that your policy has a deductible. A storm might damage your home, but you still need to buy supplies before a claim is settled. You may have a covered loss and still have expenses that aren’t part of the claim at all.

    That’s where having some cash set aside can make a hard day a little easier.

    Insurance Doesn’t Mean You Never Pay Anything

    This is one of those ideas that sounds obvious once somebody says it, but it’s easy to overlook.

    Having insurance doesn’t mean every unexpected expense becomes the insurance company’s expense.

    Depending on the policy and what happened, you may still be responsible for things like:

    • a deductible
    • expenses above a coverage limit
    • something your policy doesn’t cover
    • temporary costs while you’re dealing with the problem
    • regular repairs or maintenance that aren’t insurance claims

    And even when insurance does cover something, you may have expenses before everything is sorted out.

    That’s why I like to think of insurance and emergency savings as two different layers of protection.

    Insurance helps transfer some financial risk.

    Emergency savings gives you some room to handle the part that still belongs to you.

    You usually want both.

    Think About Your Deductible for a Minute

    Grab one of your insurance policies.

    Your auto policy is a good place to start.

    If you have collision or comprehensive coverage, look at the deductible.

    Maybe it’s $500. Maybe it’s $1,000. Maybe yours is different.

    Now ask yourself a very simple question:

    If I needed to pay that deductible this week, where would the money come from?

    Not eventually.

    This week.

    Would it come from savings?

    A credit card?

    Money you needed for rent or groceries?

    Would you have to borrow it?

    There isn’t any judgment hiding in that question. You’re simply finding out how prepared your current financial setup is for the coverage you’ve chosen.

    Your insurance policy and your bank account don’t live in separate worlds.

    They meet when something happens.

    A Lower Premium Can Mean More Risk in Your Pocket

    Here’s another place insurance and emergency savings connect.

    Sometimes choosing a higher deductible can lower an insurance premium.

    That can be useful.

    But there’s a tradeoff.

    You’re agreeing to take responsibility for more of a covered loss before the applicable insurance coverage begins paying.

    So don’t look at the premium by itself.

    Ask:

    Could I actually afford the deductible I’ve chosen?

    Saving a few dollars on a premium isn’t much help if the deductible becomes a financial crisis when you need to use the coverage.

    That doesn’t automatically mean you should choose the lowest deductible available, either.

    It means the deductible should make sense with the rest of your finances.

    Your Emergency Fund Doesn’t Have to Appear Overnight

    This is where people can get discouraged.

    They hear emergency fund and picture a giant savings account they don’t have.

    So they decide they’re already behind.

    I’d rather make the first goal smaller.

    If your emergency savings is currently $0, then getting it to $100 is progress.

    Then maybe $250.

    Then $500.

    Keep building.

    You don’t have to solve every possible financial emergency before your emergency fund becomes useful.

    A smaller cushion can still help keep a relatively small problem from landing immediately on a credit card or disrupting the rest of your monthly bills.

    The important part is to start giving unexpected expenses somewhere else to go.

    What Should You Be Saving For?

    You don’t need to predict exactly what will happen.

    Life is far too creative for that.

    Instead, look at the expenses you already know you’re responsible for.

    Start with questions like these:

    What are my insurance deductibles?

    Look at auto, renters or homeowners coverage, health insurance, and any other policies where you may have out-of-pocket costs.

    What would happen if my car needed an unexpected repair?

    Not every car problem is an insurance claim.

    What if I had to miss work or change my normal routine for a few days?

    Would that create extra transportation, food, childcare, or other costs?

    What household expense would be difficult for me to absorb today?

    That answer gives you something practical to work toward.

    You aren’t trying to save for every disaster imaginable.

    You’re building breathing room.

    Insurance Is Still Important

    I don’t want the lesson here to become, “Just save money instead.”

    That’s not what I’m saying.

    Some financial losses are far larger than most households could reasonably handle from savings alone.

    That’s one reason insurance exists.

    The goal isn’t to choose between insurance and savings.

    It’s to understand what each one is supposed to do.

    Your insurance protects against certain risks according to the terms, limits, deductibles, exclusions, and other provisions of your policy.

    Your emergency fund helps you handle some of the expenses that remain yours.

    They work better together.

    Try This: Connect Your Coverage to Your Savings

    Take ten minutes and make a short list.

    Write down:

    1. Your current emergency savings balance.
    2. Your auto insurance deductibles.
    3. Any homeowners or renters insurance deductible you have.
    4. A health insurance out-of-pocket amount you would want to be prepared for.
    5. One non-insurance emergency expense that could realistically happen in your household.

    Now look at the list.

    You don’t need to fix everything today.

    Just choose your first target.

    Maybe your first goal is $250.

    Maybe it’s enough to cover your auto deductible.

    Maybe you already have that and you’re ready for the next level.

    The right starting point is the one that moves you from “I hope nothing happens” toward “If something happens, I have a plan.”

    That’s a much more useful place to be.

    You don’t have to get your insurance and your finances perfect all at once.

    Understand one piece.

    Make one decision.

    Build one little bit of breathing room.

    Then keep going.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If you’re ready to turn the idea of an emergency fund into an actual plan, you can start small. Pick a target, look at your core expenses, and decide what you can reasonably build from here.

    Want a simple free tool to help with the next step?
    Get the free Emergency Fund Planner.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
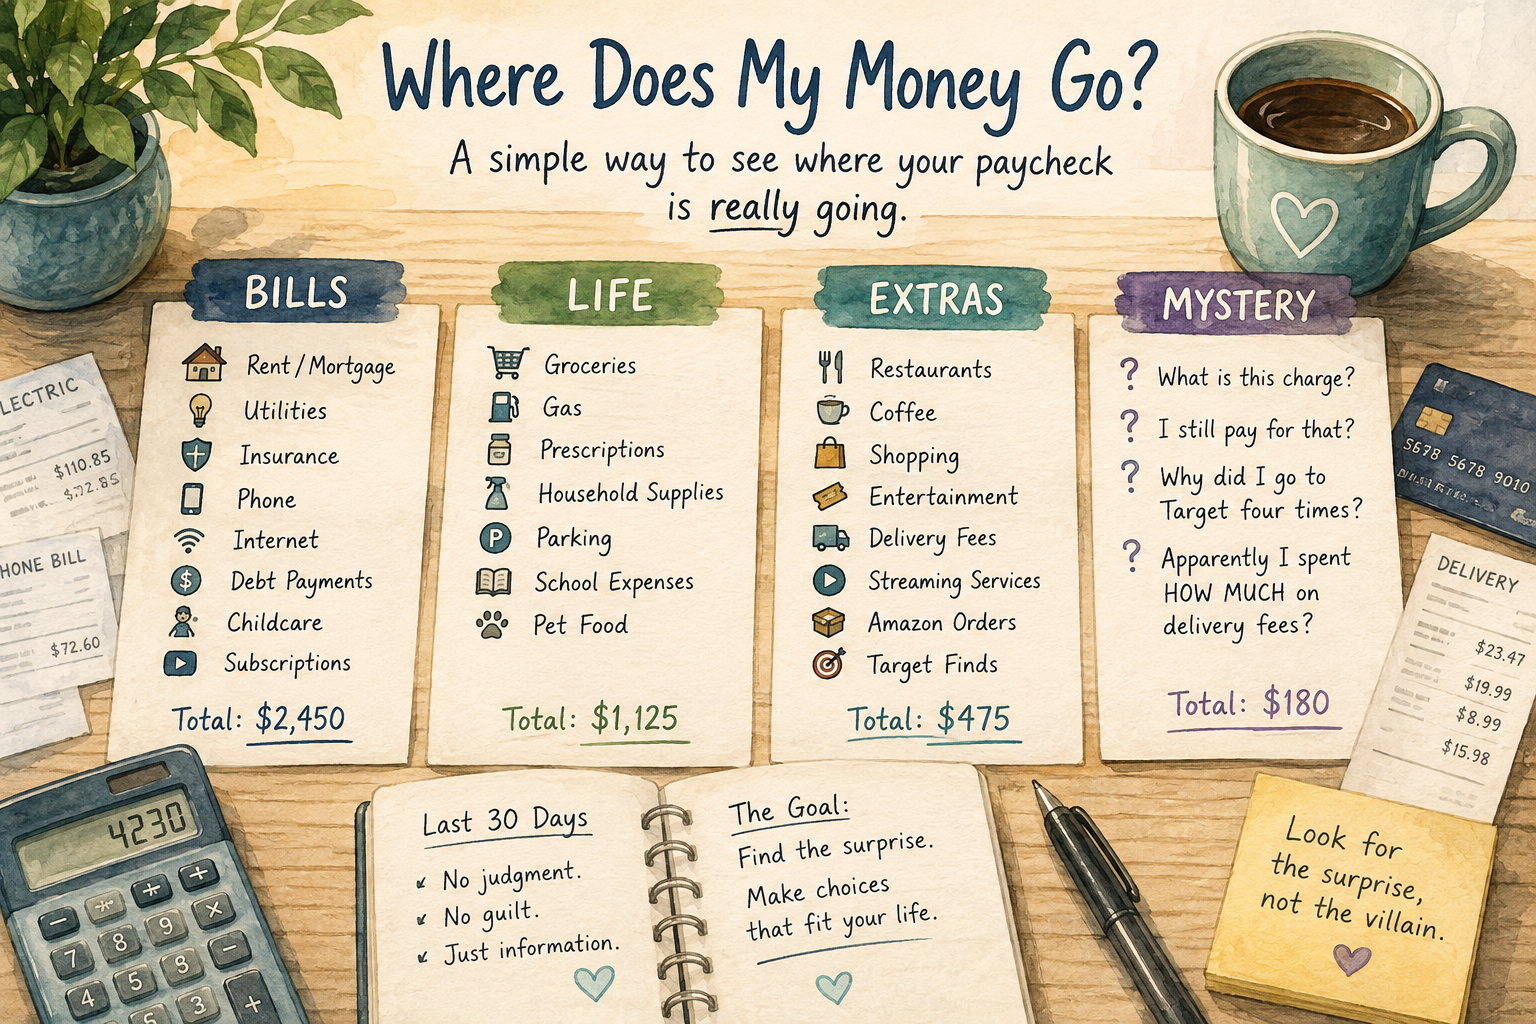
  • Where Does My Money Go? How to Find Where Your Paycheck Is Going

    Where Does My Money Go? How to Find Where Your Paycheck Is Going

    You got paid Friday.

    It’s Tuesday.

    You didn’t buy a television. You didn’t book a vacation. You didn’t even go anywhere particularly interesting.

    And somehow there’s $347 left.

    Okay.

    Before we blame the coffee, let’s figure out what actually happened.

    When money disappears faster than you expected, it’s easy to assume you’re spending too much.

    Maybe you are.

    But maybe your bills have crept up. Maybe groceries cost more than you realized. Maybe six little automatic charges hit at once. Maybe you’ve been spending $12 here and $18 there without noticing how quickly those numbers add up.

    Or maybe the math simply doesn’t work anymore.

    That’s important too.

    We’re not going to start with what you should be spending.

    We’re going to find out what you actually are spending.

    Then we can do something useful with it.

    First, Don’t Start With a Budget

    I know.

    We’re talking about money, and I’m telling you not to make a budget.

    Yet.

    A budget works much better when it’s based on real numbers.

    If you sit down and write:

    Groceries: $400
    Gas: $150
    Eating out: $100

    because those numbers seem reasonable, you’ve created a lovely budget for a person who may or may not exist.

    We need yours.

    Before deciding where your money should go next month, let’s find out where it went last month.

    Pull up your bank account. Grab your credit card statement too, if you use one regularly.

    We’re looking at roughly the last 30 days.

    No judgment. No guilt. No promising that you’ll never order takeout again.

    We’re investigating.

    Meet Bills, Life, Extras and Mystery

    We’re going to make this very complicated.

    Four categories.

    That’s it.

    Take the spending from the last month and sort it into:

    Bills

    These are the things that show up because life apparently requires a subscription fee.

    Rent or mortgage. Utilities. Insurance. Phone. Internet. Minimum debt payments. Childcare. Regular subscriptions.

    Anything you’re committed to paying on a recurring basis belongs here.

    Some of these amounts may change a little month to month. That’s fine.

    We’re looking for the basic cost of keeping your life running.

    Life

    This is the everyday stuff.

    Groceries. Gas. Prescriptions. Household supplies. Parking. School expenses. Pet food.

    The things you buy because people, cars, houses and apparently dogs require constant maintenance.

    These aren’t necessarily fixed bills, but they’re also not exactly optional.

    You have to eat. You may have to drive to work.

    The dog remains strangely unwilling to purchase his own food.

    Life costs money.

    Put it here.

    Extras

    Here’s where things get interesting.

    Restaurants. Coffee. Shopping. Entertainment. Delivery fees. Streaming services you could live without. Random Amazon orders.

    That thing Target convinced you was essential even though you went in for toothpaste.

    Extras aren’t bad.

    Let me say that again.

    Extras aren’t bad.

    Money is allowed to make your life enjoyable.

    We’re not creating a budget where you sit at home in the dark eating beans while congratulating yourself on your financial discipline.

    We just want to know how much is going here.

    Mystery

    You knew this category was coming.

    Mystery is:

    “What is this $27.43 charge?”

    “I still pay for that?”

    “Why did I go to Target four times?”

    “Apparently I spent how much on delivery fees?”

    These are the transactions you didn’t remember making, charges you don’t recognize immediately, subscriptions you’d forgotten about, and little purchases that somehow became a much bigger number when you added them together.

    Mystery is often where we learn something.

    Not necessarily something we wanted to learn.

    But something useful.

    Add Up Your Monthly Spending

    Once everything has a home, total each category.

    Let’s say you end up with:

    Bills: $2,450
    Life: $1,125
    Extras: $475
    Mystery: $180

    Now we’re getting somewhere.

    Maybe you expected Extras to be the problem and discover they really aren’t.

    Maybe Bills are eating far more of your income than you realized.

    Maybe groceries have quietly climbed by $200 a month.

    Maybe Mystery contains four subscriptions and $96 worth of fees you’d barely noticed.

    This is why we looked before we started cutting.

    You can’t fix a money problem very well when you’re guessing what the problem is.

    Look for the Surprise, Not the Villain

    Personal finance loves finding villains.

    Coffee. Avocado toast. Streaming services. Eating out.

    Whatever we’re all supposedly doing wrong this year.

    I’m less interested in finding something to blame.

    I want to find the surprise.

    What number made you stop and say:

    “Wait. Really?”

    Maybe it’s groceries.

    Maybe it’s insurance.

    Maybe it’s takeout.

    Maybe it’s a collection of $9.99 charges quietly having a party in your checking account.

    That’s where I’d look first.

    Because the biggest opportunity isn’t always where somebody on the internet told you it would be.

    It’s where your numbers say it is.

    Check the Small Stuff—But Don’t Obsess Over It

    Small purchases add up. They absolutely do.

    Five dollars here. Twelve dollars there. Do that often enough and eventually we’re talking about real money.

    But I don’t want you spending forty minutes feeling guilty about a $4 coffee while ignoring the $175 bill that might be worth investigating.

    I’d look at the big numbers first.

    Housing. Transportation. Insurance. Debt payments. Phone. Internet. Subscriptions. Groceries.

    Then look at the smaller stuff.

    If you’re spending $160 a month on something you barely use, that’s interesting.

    If you’re spending $18 a month on something you genuinely enjoy and can afford?

    Maybe we leave it alone.

    Not every expense needs to be optimized within an inch of its life.

    Look for Money That’s Leaving Automatically

    Automatic payments are wonderful.

    Until you forget about them.

    Go through your transactions and look specifically for recurring charges.

    Streaming services. Apps. Cloud storage. Memberships. Software. Subscriptions.

    Anything else that quietly renews while you’re busy doing something more interesting.

    Here are three questions I like:

    Do I still use this?

    Would I notice if it disappeared?

    Would I sign up for it again today at this price?

    That last one is my favorite.

    Something you happily paid $8 for three years ago might now cost $17.99.

    And apparently nobody thought to ask whether you were still enjoying yourself.

    If you’d happily buy it again, great.

    If you wouldn’t?

    That’s one worth looking at.

    Then Look at the Expenses You Can’t Just Cancel

    This part matters.

    Sometimes you go through everything and discover there really isn’t much nonsense.

    You’re not secretly spending $600 a month on lattes. You’re not paying for fourteen streaming services. You’re not ordering packages every afternoon.

    Your rent is high.

    Groceries are high.

    Insurance went up.

    Gas isn’t cheap.

    And your paycheck hasn’t kept up.

    Sometimes the numbers are tight because the numbers are tight.

    That’s useful information too.

    Instead of asking:

    “How do I stop wasting money?”

    we can start asking:

    “Which of these bigger expenses might actually be changeable?”

    Maybe insurance is worth shopping.

    Maybe it’s worth checking whether the phone or internet bill can be reduced.

    Maybe a debt payment needs a larger strategy.

    Maybe income is part of the problem.

    None of those is necessarily an easy fix.

    But at least we’re looking at the real problem instead of blaming a cup of coffee for something it didn’t do.

    Don’t Forget the Bills That Don’t Come Every Month

    Car registration. Birthdays. Annual subscriptions. Car maintenance. Vet visits.

    They don’t happen every month, but they still take money when they arrive.

    That’s why I like to remember:

    Not monthly doesn’t mean unexpected.

    For now, make note of the expenses you notice that come around occasionally.

    We’ll talk separately about how to plan for them instead of letting them surprise the budget every time.

    Now We Can Make a Budget

    This is where budgeting becomes useful.

    Because now we’re not inventing numbers.

    We know roughly what Bills cost. We know what Life costs. We’ve seen Extras. We’ve investigated Mystery.

    And we’ve started noticing expenses that don’t happen every month.

    Now you can decide what you want the next month to look like.

    Maybe you want to reduce takeout by $75.

    Maybe there are two subscriptions you no longer want.

    Maybe you’d like to set aside $50 for car maintenance or start putting $25 toward emergency savings.

    Whatever makes sense for your situation.

    If you use a budgeting worksheet or other budgeting tool, this is also where it becomes much more useful.

    Instead of staring at blank categories and guessing what numbers you’re supposed to put in them, you can start with what you just found:

    Real income. Real bills. Real spending.

    Then make adjustments from there.

    That’s a budget you actually have a chance of using.

    Don’t Try to Fix Everything at Once

    You’ve gone through the numbers.

    You’ve discovered six things you’d like to change.

    Excellent.

    Please don’t change all six tomorrow.

    Pick one or two places to start.

    Maybe you cancel something you don’t use. Maybe you try a different grocery target. Maybe you move $25 into savings on payday.

    Give yourself a chance to see whether the change actually works.

    Then adjust again.

    Money habits are much easier to change when we’re not trying to reinvent our entire financial life on a Sunday afternoon.

    Do This Again Next Month

    Not forever.

    I’m not asking you to spend the rest of your life categorizing every $6 purchase.

    Do it again next month.

    See what changed.

    Did Mystery get smaller?

    Did the grocery number surprise you again?

    Did you actually save the $75 you planned to save?

    Did something completely different happen?

    That’s how you turn a budget from something you wrote once into something that actually reflects your life.

    Eventually, you won’t need to investigate quite so much.

    You’ll know your numbers.

    So…Where Did Your Money Go?

    Maybe you spent more on Extras than you realized.

    Maybe your Bills have quietly climbed.

    Maybe Life simply costs more than it used to.

    Maybe Mystery was having a particularly good month.

    Or maybe you discover you’re actually doing a pretty decent job with the money you have.

    That’s worth knowing too.

    This isn’t about catching yourself doing something wrong.

    It’s about stopping the guessing.

    Pull the statements. Look at the last 30 days.

    Sort the spending into:

    Bills. Life. Extras. Mystery.

    Find the surprise.

    Then decide what you want to change.

    That’s when a budget starts becoming useful.

    Not because somebody handed you percentages and told you what your life should cost.

    Because you finally know what your life costs.

    And that’s a much better place to start.

    Want a Little More Help?

    Once you know where your paycheck is going, the next step is keeping an eye on it without turning money management into an all-day project.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.


    More Money conversations are coming to Talkin With Emma. We’ll keep working through this stuff one question at a time.

    This article is for general educational and informational purposes only and isn’t intended as individualized financial, investment, tax, or legal advice. Everyone’s financial situation is different. Consider your own circumstances and, when appropriate, consult a qualified financial or other professional before making significant financial decisions.

    Share This Conversation