Tag: personal finance

  • Should I Pay My Credit Card Before the Statement Date or the Due Date?

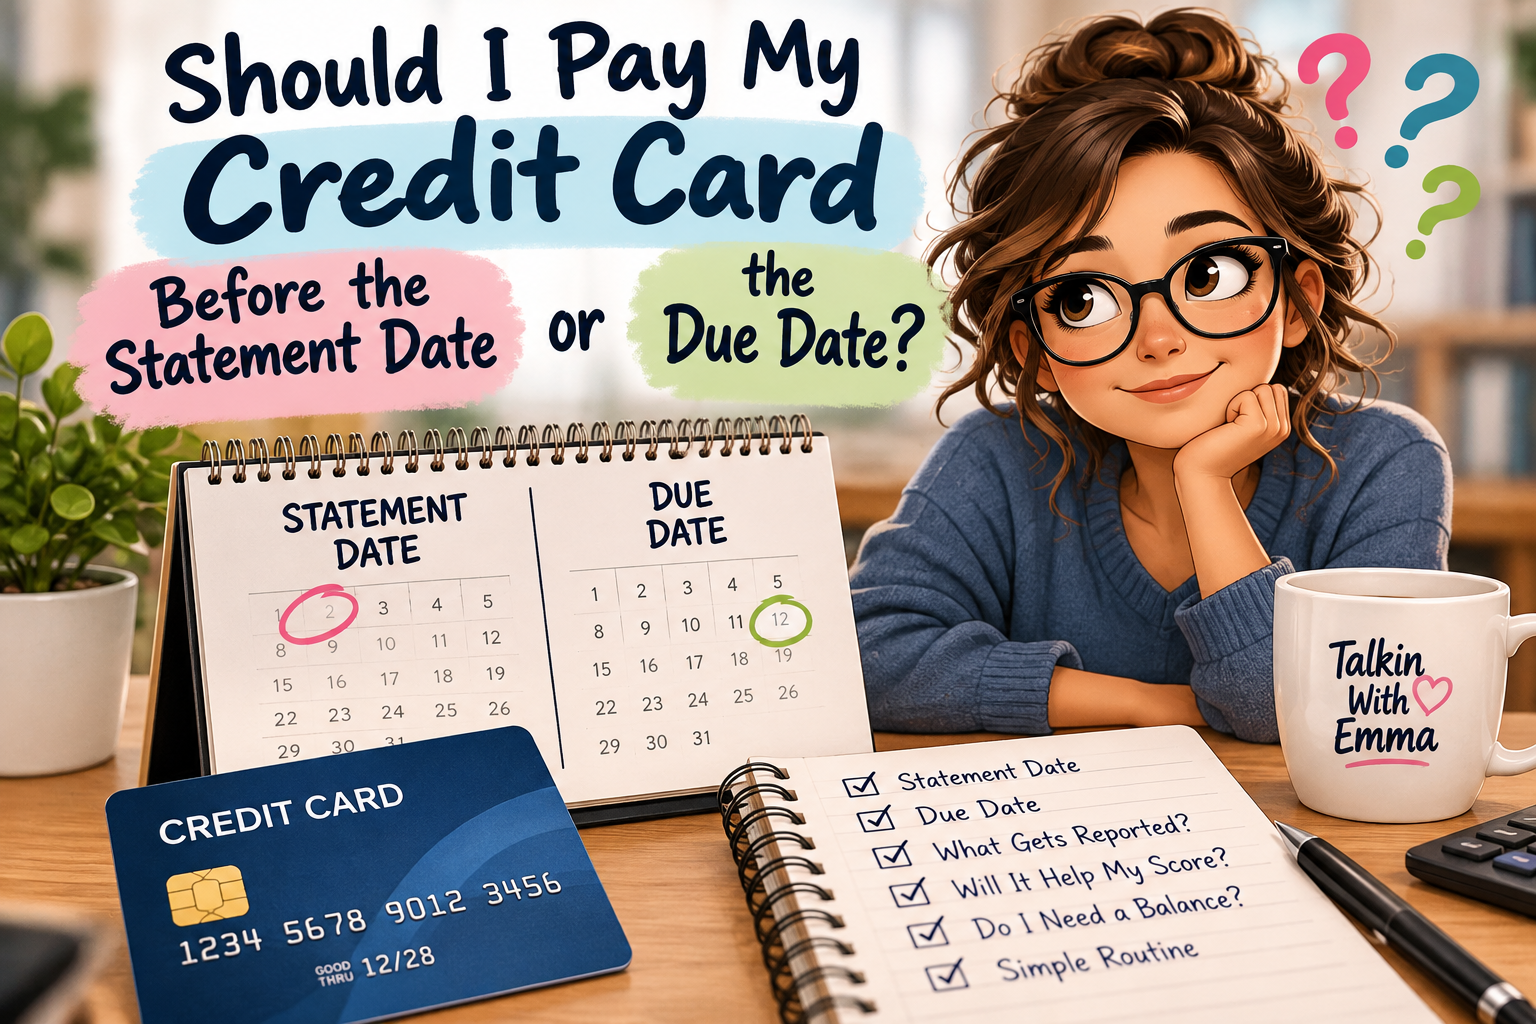
    Should I Pay My Credit Card Before the Statement Date or the Due Date?

    If you have ever tried to figure out the “right” day to pay a credit card, the internet can make a simple bill feel like a strategy game.

    Pay before the statement date. Pay on the due date. Pay twice a month. Leave a tiny balance. Never leave a balance.

    That is a lot of rules for something that should be much easier.

    Here is the short answer: If your goal is to make an on-time payment and, when your card has an applicable grace period, avoid interest on purchases, focus on paying the amount required by your card agreement by the due date. If you are trying to lower the balance that may appear on your credit reports, making a payment before the statement closes may help because many issuers report account information around the end of a billing cycle. You do not need to carry a balance or pay interest to build credit.

    First, What Is the Statement Date?

    Your credit card runs on billing cycles. At the end of a cycle, the card company creates a statement showing what happened during that period.

    That statement usually includes your statement balance, minimum payment, payment due date, interest and fees, credit limit, and a list of transactions.

    Think of the statement closing date as the point when the card company takes a snapshot of that billing cycle and prepares your bill.

    Then What Is the Due Date?

    The due date is the deadline for the payment shown on your statement.

    At minimum, you need to make the required minimum payment by the due date to keep the payment from being late. Federal rules generally require card issuers to deliver or mail statements at least 21 days before the payment is due.

    If your card provides a grace period on purchases and you meet its terms, paying the applicable statement balance in full by the due date can generally let you avoid interest on those purchases. Check your own card agreement because grace periods are not required and their terms can differ.

    So Why Would Anyone Pay Before the Statement Closes?

    This is where credit utilization enters the conversation.

    Credit utilization is basically how much of your available revolving credit you are using. If you have a $1,000 limit and a $500 reported balance, that card is showing 50% utilization.

    Credit scoring models can consider utilization. The balance that appears on a credit report is not necessarily the balance sitting in your account on the exact day someone checks your credit. Credit card companies periodically report account information to the credit bureaus, and the timing can vary by issuer.

    That means a person who pays a card in full every month can still have a balance reported.

    For example, imagine you have a $1,000 limit. You spend $600 during the month. Your statement closes showing $600, and then you pay that $600 in full before the due date.

    You did not do anything wrong. You paid your bill as agreed. But if the issuer reported the $600 balance, your credit report may temporarily show relatively high utilization on that card.

    If you had paid $400 before the statement closed, the statement might instead close with $200, depending on when the payment posted and when the issuer reports. That could mean a lower reported balance.

    That is the practical reason some people make an early payment. It is not because paying on the due date is automatically bad.

    Do I Need to Leave a Balance to Build Credit?

    No.

    This is one of those credit myths that refuses to go away.

    You do not need to carry debt from one billing cycle to the next and pay interest just to prove that you can use credit. On-time account history can help build credit without deliberately paying interest.

    If you can pay your statement balance in full and your card’s grace-period terms apply, paying it by the due date is usually the less expensive approach.

    What Is the Difference Between the Minimum Payment and the Statement Balance?

    This distinction matters much more than memorizing a special payment trick.

    The minimum payment is the smallest amount your issuer says you must pay by the due date to satisfy that month’s required payment.

    The statement balance is the balance shown when that billing cycle closed.

    If you pay only the minimum, the rest does not disappear. You may pay interest on the unpaid amount, and paying a debt down can take much longer.

    If money is tight and you cannot pay the full statement balance, do not let “I can’t pay it all” turn into “so I won’t pay anything.” Making at least the required minimum payment on time is important. Then look at what you can realistically pay above it.

    Is It Bad to Pay My Credit Card More Than Once a Month?

    No. You can generally make more than one payment during a billing cycle.

    For some people, that is useful. Maybe you get paid every two weeks and prefer paying part of the card each payday. Maybe making an early payment helps keep your reported balance lower. Maybe smaller payments simply make the household budget easier to manage.

    Those are practical reasons.

    What you do not need is a complicated schedule because someone online promised that paying on two magic days will automatically boost your score.

    Please Don’t Turn This Into Another Credit-Score Game

    Once people learn that reported balances can affect utilization, it is easy to start micromanaging every purchase and payment.

    You probably do not need to do that.

    Credit scores can matter, especially when you are preparing to apply for a mortgage, auto loan, apartment, or another product where your credit will be reviewed. In that situation, paying balances down before they are reported may be useful if utilization is high.

    But for everyday credit management, the bigger habits are much less exciting:

    • Know your due date.
    • Make at least the required payment on time.
    • Pay the statement balance in full when you reasonably can and when that fits your card’s terms.
    • Keep an eye on how much of your available credit you are using.
    • Read your statements.
    • Do not spend money just because credit is available.

    Those habits are not flashy enough for a viral “credit hack,” but they are much more useful.

    A Simple Credit Card Routine

    If you want to keep this simple, try this:

    1. Check your statement every month. Make sure the transactions look right and note the statement balance, minimum payment, and due date.
    2. Set up a reminder or autopay. At the very least, protect yourself from accidentally missing the required payment.
    3. Pay the statement balance in full when you can. If your card has an applicable grace period and you meet its conditions, this can help you avoid purchase interest.
    4. If your reported balance is high, consider paying earlier. An extra payment before the statement closes may reduce the balance that gets reported, depending on your issuer’s reporting schedule.
    5. If you cannot pay in full, make a plan instead of avoiding the bill. Pay at least the required minimum on time, then decide how much extra you can put toward the balance.

    That is enough. You do not need to turn paying a credit card into a part-time job.

    Quick Questions

    Does paying before the statement date help my credit score?

    It can help lower the balance that may be reported to the credit bureaus, which may lower your reported utilization. Whether that changes a particular score depends on the information in your credit report and the scoring model being used.

    When do credit card companies report balances?

    Reporting schedules vary. Many issuers report periodically around the end of a billing cycle, but you should not assume every issuer reports on the same day. You can check your credit reports to see what balance is appearing and ask your issuer about its reporting practices.

    Should I leave a small balance on my card?

    You do not need to carry a balance from month to month or pay interest in order to build credit.

    Should I pay on the statement date or due date?

    You do not have to wait for either date to make a payment. The due date is the important deadline for making the required payment on time. Paying earlier can be useful for budgeting or for reducing the balance that may be reported.

    What if I cannot afford the statement balance?

    Pay at least the required minimum by the due date if you can, then pay as much additional principal as your budget reasonably allows. If you are struggling to make even the minimum payment, contact the card issuer as soon as possible rather than waiting until after you miss it.

    The Bottom Line

    The statement date and the due date do two different jobs.

    The statement date closes out a billing cycle and helps determine what appears on that month’s statement. The due date tells you when the required payment must be received.

    If you want the simplest rule, start here: pay on time, pay the statement balance in full when you reasonably can, and do not carry debt just because someone told you it helps your credit.

    Once you understand what the dates and numbers actually mean, credit gets a lot less mysterious.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If you’re trying to make credit-card payments fit more comfortably into the rest of your month, it can help to look at the whole money picture instead of one due date at a time.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.
    Share This Conversation
  • Why Does My Bank Account Say I Have Money When I’m Still Broke?

    Why Does My Bank Account Say I Have Money When I’m Still Broke?

    You check your bank account and see $600.

    For about three seconds, that feels pretty good.

    Then you remember the electric bill comes out tomorrow.

    Car insurance is due Friday.

    You bought groceries yesterday, but that charge is still sitting there as pending.

    And at least some of that money needs to stay right where it is because rent is coming.

    So, yes. There is $600 in your account.

    That does not mean you have $600 to spend.

    This is one of those money problems that gets much easier once somebody explains what is actually happening. Your bank balance is giving you useful information. It just is not giving you the whole picture.

    Let’s sort out the rest of it.

    What Does My Bank Balance Actually Tell Me?

    Your bank balance tells you how much money is in the account according to the transactions your bank has processed.

    That’s important.

    But your bank does not know your plan.

    It does not know that you need $150 of that money for the electric bill.

    It does not know that you need enough gas to get through next week.

    It definitely does not know that the $100 sitting there is the beginning of the money you are setting aside for your car registration.

    You know those things.

    That’s why I don’t want you making spending decisions based only on the big number at the top of your banking app.

    That number answers:

    How much money is in my account?

    What we really need to know is:

    How much of that money is actually available for me to spend?

    Those are not always the same number.

    What Is the Difference Between My Current Balance and Available Balance?

    Your banking app may show you a current balance and an available balance.

    They sound like they should make everything perfectly clear.

    Naturally, they do not.

    Your current balance generally reflects the transactions that have already posted to your account.

    Your available balance usually does a little more work for you. It may account for pending transactions or holds the bank already knows about.

    So if you spent $60 at the grocery store this morning and that transaction is still pending, your available balance may give you a better picture of what is actually left.

    That’s helpful.

    But there is still a problem.

    Your bank only knows about the things your bank knows about.

    If your $175 utility bill is due Thursday but has not been paid yet, your bank cannot reserve that $175 for you.

    If you need $80 for groceries until payday, your bank does not set that aside.

    If your car registration is due next month, your banking app is not going to tap you on the shoulder and say, “Emma, maybe leave some of this alone.”

    That’s your part of the job.

    Why Can I Have Money in the Bank and Still Be Broke?

    Because some of that money may already belong to something else.

    Let’s say you have $600 available right now.

    Before you get paid again, you need:

    • $175 for utilities
    • $125 for car insurance
    • $100 for groceries
    • $60 for gas
    • $75 for another bill

    That’s $535.

    You still have $600 in the bank.

    But $535 already has somewhere to go.

    That leaves $65 that is not already committed.

    Now imagine looking at that $600 balance and deciding a $100 purchase is fine because you have plenty of money in the account.

    You do have enough to make the purchase.

    You just don’t have enough to make the purchase and do everything else that money needs to do.

    That’s the part that gets us.

    The purchase works today.

    The problem shows up Friday.

    How Do I Know How Much Money I Can Actually Spend?

    We can make this pretty simple.

    Start with the money you have available.

    Then subtract the money you need before more income comes in.

    Money available now − money already needed = money that is not committed

    Let’s try it.

    You have $900.

    Before your next paycheck, you need:

    • $500 for bills
    • $150 for groceries and gas
    • $100 for an expense you already know is coming

    So:

    $900 − $500 − $150 − $100 = $150

    That $150 is much more useful to me than the $900 at the top of the banking app.

    I think of it as safe-to-spend money.

    It is the money left after we have accounted for the things that need to happen first.

    Does that mean you need to immediately spend the whole $150?

    Of course not.

    It means you now know what you’re actually working with.

    And knowing is a lot easier to work with than hoping.

    Don’t Forget the Expenses That Don’t Happen Every Month

    Monthly bills usually aren’t the hardest ones to remember.

    Rent has a way of reminding us it exists.

    So does the electric company.

    It’s the other expenses that like to disappear for a while and then wander back into our lives asking for $300.

    Car registration.

    School expenses.

    Annual memberships.

    Holiday spending.

    Vet visits.

    Insurance premiums.

    Birthdays.

    Home repairs.

    Car maintenance.

    Medical copays.

    None of these is necessarily unexpected.

    We just don’t pay them every month, so they’re easy to leave out when we’re thinking about what our money needs to do.

    If this keeps happening to you, I talked more about why a budget can fail even when the math works.

    One simple thing you can do is start turning those larger future expenses into smaller current ones.

    Suppose you know you’ll need $300 six months from now.

    Finding $300 all at once might hurt.

    Setting aside $50 a month for six months may be much easier.

    Same $300.

    Much less drama.

    What If I Use Cash Instead of a Banking App?

    Good.

    This still works.

    You do not need an app, spreadsheet, online bank account, or fancy budgeting system to know what your money needs to do.

    If you use cash, envelopes can actually make this idea very easy to see.

    Maybe you have:

    • $200 in the rent envelope
    • $100 in groceries
    • $60 in gas
    • $75 in utilities
    • $50 in savings
    • $40 in spending money

    Altogether, you have $525.

    But you wouldn’t dump all six envelopes onto the table, count the money, and decide you have $525 available for dinner and shopping.

    The labels matter.

    Your rent money is still rent money.

    Your gas money is still gas money.

    And your $40 of spending money is the part you can spend without stealing from something else.

    A budget is doing the same job.

    You can keep yours on paper, in envelopes, on your phone, in a spreadsheet, or wherever it makes sense to you.

    I care much more about whether you know what the money is supposed to do than where you write it down.

    What If My Safe-to-Spend Number Is Negative?

    Let’s say you do the math and get this:

    Money available: $700

    Money you need before payday: $850

    Difference: -$150

    Well, that’s not the answer we were hoping for.

    But I would much rather you know about that $150 shortage now than discover it three days before payday.

    A negative number is information.

    It tells us we have a problem to solve.

    Now we can ask useful questions.

    What absolutely has to be paid before payday?

    What can wait?

    Is there a bill due date that can be moved?

    Is there an expense we can reduce this time?

    Is this a one-time problem, or are we coming up short by roughly the same amount every month?

    That last question matters.

    If this happens once because three unusual expenses landed in the same week, we solve this week.

    If you’re $150 short every single month, we have a bigger problem to work on.

    Neither problem gets easier by refusing to look at the number.

    Finding it early gives you time to make decisions.

    Do I Need a Complicated Budget to Do This?

    No.

    And I really don’t want you building a complicated budget just because somebody told you a “real” budget needs 47 categories and a color-coded spreadsheet.

    If you love spreadsheets, wonderful.

    Use one.

    If you would rather use a notebook and a pen, use those.

    If cash envelopes make sense to your brain, get the envelopes.

    Your budget needs to help you answer a few questions:

    What money is coming in?

    What needs to be paid?

    When does it need to be paid?

    What expenses do I know are coming later?

    What can I safely spend after I account for those things?

    If your system can answer those questions, we have something useful.

    We can make it prettier later.

    Your Bank Balance Needs Context

    I don’t want you to stop checking your bank balance.

    Please check it.

    We just aren’t going to ask that one number to do a job it cannot do.

    If your account says $600, then yes, you have $600 in the account.

    But your budget may tell you:

    $175 is for utilities.

    $125 is for insurance.

    $100 is for groceries.

    $60 is for gas.

    $75 is for another bill.

    And $65 is left.

    Now that $600 means something.

    That’s the difference.

    Instead of looking at your account and asking:

    “Do I have money?”

    Try asking:

    “What does this money need to do before I get paid again?”

    That question will tell you a lot more.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If your bank balance keeps giving you the wrong impression, a simple check-in can help you give the money in your account a job before you decide what is safe to spend.

    Want a simple free tool to help with the next step?
    Get the free Monthly Money Check-In.

    Want to go a little deeper?
    Take a look at Let’s Talk About Budgeting.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.

    Share This Conversation
  • Why an Emergency Fund Matters Even When You Have Insurance

    Why an Emergency Fund Matters Even When You Have Insurance

    Insurance can protect you from some very expensive problems.

    So if you have insurance, do you really need an emergency fund too?

    Yes.

    Not because your insurance isn’t doing its job. The two simply have different jobs.

    Insurance can help with certain covered losses. An emergency fund gives you money you can reach when life creates an expense right now.

    And sometimes those two things meet in the same afternoon.

    You might have a car accident and discover that your policy has a deductible. A storm might damage your home, but you still need to buy supplies before a claim is settled. You may have a covered loss and still have expenses that aren’t part of the claim at all.

    That’s where having some cash set aside can make a hard day a little easier.

    Insurance Doesn’t Mean You Never Pay Anything

    This is one of those ideas that sounds obvious once somebody says it, but it’s easy to overlook.

    Having insurance doesn’t mean every unexpected expense becomes the insurance company’s expense.

    Depending on the policy and what happened, you may still be responsible for things like:

    • a deductible
    • expenses above a coverage limit
    • something your policy doesn’t cover
    • temporary costs while you’re dealing with the problem
    • regular repairs or maintenance that aren’t insurance claims

    And even when insurance does cover something, you may have expenses before everything is sorted out.

    That’s why I like to think of insurance and emergency savings as two different layers of protection.

    Insurance helps transfer some financial risk.

    Emergency savings gives you some room to handle the part that still belongs to you.

    You usually want both.

    Think About Your Deductible for a Minute

    Grab one of your insurance policies.

    Your auto policy is a good place to start.

    If you have collision or comprehensive coverage, look at the deductible.

    Maybe it’s $500. Maybe it’s $1,000. Maybe yours is different.

    Now ask yourself a very simple question:

    If I needed to pay that deductible this week, where would the money come from?

    Not eventually.

    This week.

    Would it come from savings?

    A credit card?

    Money you needed for rent or groceries?

    Would you have to borrow it?

    There isn’t any judgment hiding in that question. You’re simply finding out how prepared your current financial setup is for the coverage you’ve chosen.

    Your insurance policy and your bank account don’t live in separate worlds.

    They meet when something happens.

    A Lower Premium Can Mean More Risk in Your Pocket

    Here’s another place insurance and emergency savings connect.

    Sometimes choosing a higher deductible can lower an insurance premium.

    That can be useful.

    But there’s a tradeoff.

    You’re agreeing to take responsibility for more of a covered loss before the applicable insurance coverage begins paying.

    So don’t look at the premium by itself.

    Ask:

    Could I actually afford the deductible I’ve chosen?

    Saving a few dollars on a premium isn’t much help if the deductible becomes a financial crisis when you need to use the coverage.

    That doesn’t automatically mean you should choose the lowest deductible available, either.

    It means the deductible should make sense with the rest of your finances.

    Your Emergency Fund Doesn’t Have to Appear Overnight

    This is where people can get discouraged.

    They hear emergency fund and picture a giant savings account they don’t have.

    So they decide they’re already behind.

    I’d rather make the first goal smaller.

    If your emergency savings is currently $0, then getting it to $100 is progress.

    Then maybe $250.

    Then $500.

    Keep building.

    You don’t have to solve every possible financial emergency before your emergency fund becomes useful.

    A smaller cushion can still help keep a relatively small problem from landing immediately on a credit card or disrupting the rest of your monthly bills.

    The important part is to start giving unexpected expenses somewhere else to go.

    What Should You Be Saving For?

    You don’t need to predict exactly what will happen.

    Life is far too creative for that.

    Instead, look at the expenses you already know you’re responsible for.

    Start with questions like these:

    What are my insurance deductibles?

    Look at auto, renters or homeowners coverage, health insurance, and any other policies where you may have out-of-pocket costs.

    What would happen if my car needed an unexpected repair?

    Not every car problem is an insurance claim.

    What if I had to miss work or change my normal routine for a few days?

    Would that create extra transportation, food, childcare, or other costs?

    What household expense would be difficult for me to absorb today?

    That answer gives you something practical to work toward.

    You aren’t trying to save for every disaster imaginable.

    You’re building breathing room.

    Insurance Is Still Important

    I don’t want the lesson here to become, “Just save money instead.”

    That’s not what I’m saying.

    Some financial losses are far larger than most households could reasonably handle from savings alone.

    That’s one reason insurance exists.

    The goal isn’t to choose between insurance and savings.

    It’s to understand what each one is supposed to do.

    Your insurance protects against certain risks according to the terms, limits, deductibles, exclusions, and other provisions of your policy.

    Your emergency fund helps you handle some of the expenses that remain yours.

    They work better together.

    Try This: Connect Your Coverage to Your Savings

    Take ten minutes and make a short list.

    Write down:

    1. Your current emergency savings balance.
    2. Your auto insurance deductibles.
    3. Any homeowners or renters insurance deductible you have.
    4. A health insurance out-of-pocket amount you would want to be prepared for.
    5. One non-insurance emergency expense that could realistically happen in your household.

    Now look at the list.

    You don’t need to fix everything today.

    Just choose your first target.

    Maybe your first goal is $250.

    Maybe it’s enough to cover your auto deductible.

    Maybe you already have that and you’re ready for the next level.

    The right starting point is the one that moves you from “I hope nothing happens” toward “If something happens, I have a plan.”

    That’s a much more useful place to be.

    You don’t have to get your insurance and your finances perfect all at once.

    Understand one piece.

    Make one decision.

    Build one little bit of breathing room.

    Then keep going.

    Friendly conversations. Practical tools. Clear explanations.

    Want a Little More Help?

    If you’re ready to turn the idea of an emergency fund into an actual plan, you can start small. Pick a target, look at your core expenses, and decide what you can reasonably build from here.

    Want a simple free tool to help with the next step?
    Get the free Emergency Fund Planner.

    Want a clearer, beginner-friendly way to work through your money?
    Take a look at Let’s Talk About Money.

    Want practical insurance, money, and everyday-life help in your inbox?
    Join Emma’s Mailbox.
    Share This Conversation