Insurance is one of those things that is very easy to set up…
and then completely forget about.
You buy the policy.
Set up autopay.
Put the paperwork somewhere safe.
And move on with your life.
Which is fine.
Until your life changes and your insurance does not.
Because the coverage that made perfect sense three years ago may not make quite as much sense today.
That does not mean you need to rethink every insurance policy every time something happens.
New haircut?
Probably safe to leave the insurance company out of it.
But some life changes are worth a second look.
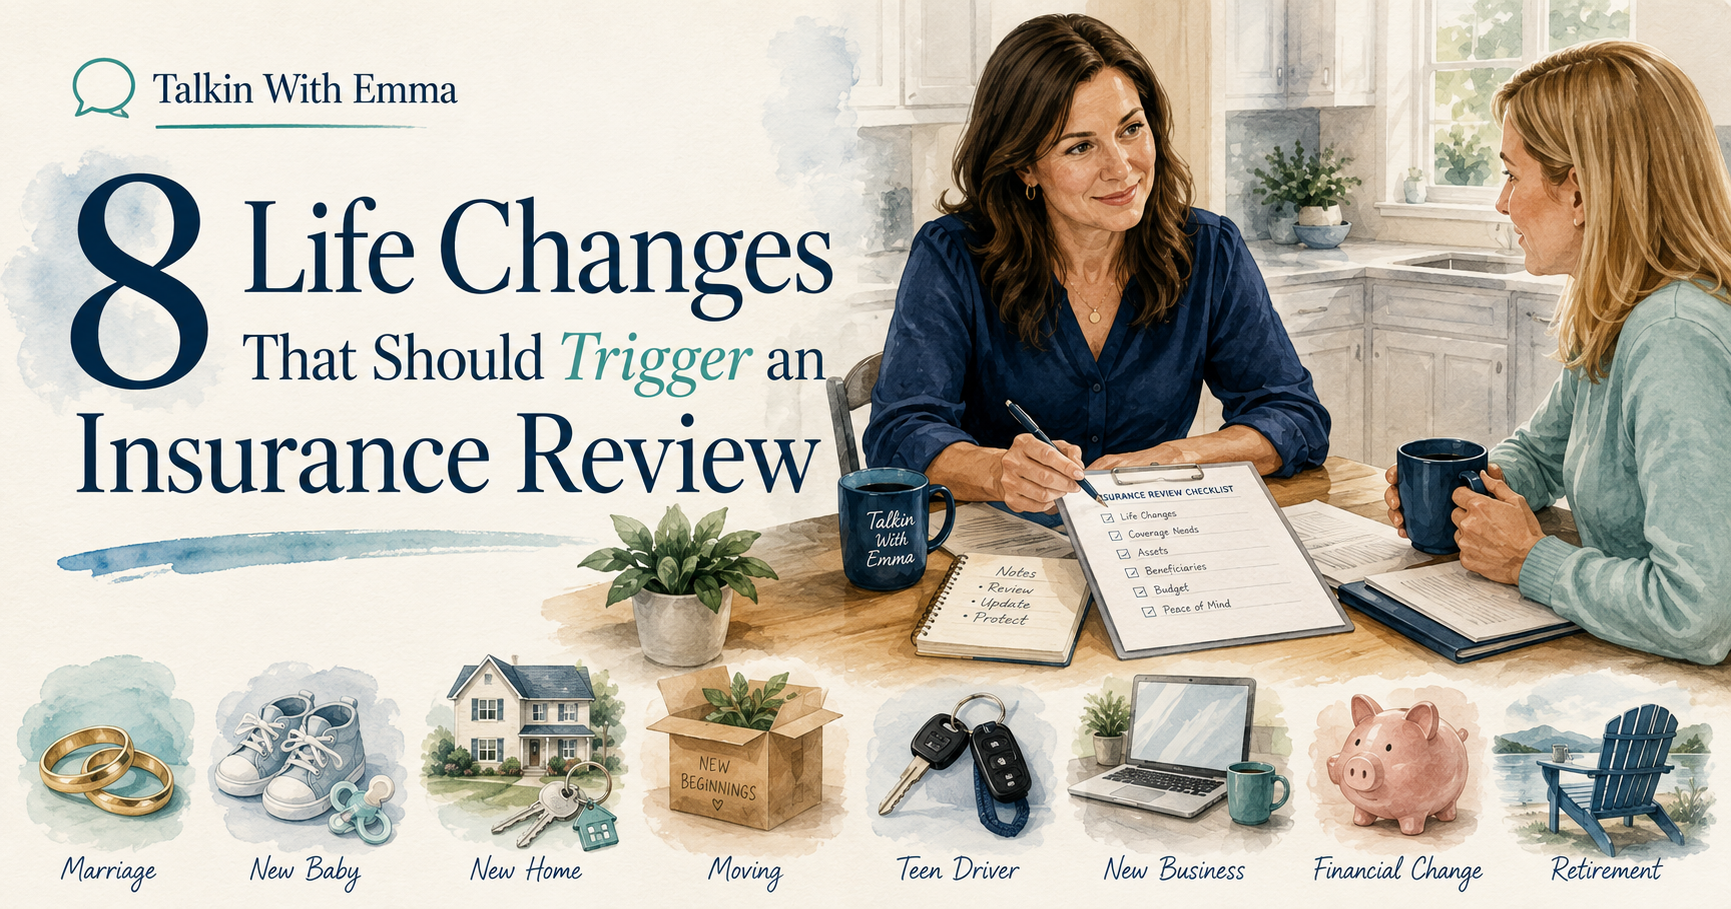
Here are eight.
1. You Got Married
Marriage combines more than closets and opinions about how the dishwasher should be loaded.
You may also be combining:
Income.
Assets.
Debts.
Vehicles.
Homes.
Bills.
Financial responsibilities.
And people who now depend on each other in ways they did not before.
That is a good reason to look at your insurance again.
Start with what each of you already has.
Auto insurance.
Renters or homeowners insurance.
Life insurance.
Health insurance.
Anything else.
Then ask:
Are we paying for the same thing twice?
Did anything important change?
Is there something one of us assumed the other person already handled?
Do any beneficiaries need to be reviewed?
Do not assume getting married automatically updates everything.
Insurance companies are many things.
Wedding planners are generally not one of them.
If the whole insurance picture still feels a little fuzzy, Let’s Talk About Insurance is a good place to start with the basics.
2. You Got Divorced or Separated
This deserves just as much attention as getting married.
Maybe you are separating vehicles.
Moving into different homes.
Changing who owns what.
Changing financial responsibilities.
Changing beneficiaries.
Changing who is covered under which policy.
This is not the time to think:
“I am sure that gets handled automatically.”
Find out.
Look at each policy and ask:
Who is the named insured?
Which vehicles are listed?
Who owns them?
Where are they kept?
Who is driving them?
Who should be a beneficiary where that applies?
Who is responsible for the homeowners or renters policy now?
Divorce can involve legal and financial issues far beyond insurance, so bring in the right professionals when you need them.
From the insurance side, the goal is simpler:
Make sure the policies match the life you are actually living now.
3. You Had a Baby—or Someone New Depends on You
Babies have a remarkable ability to change almost everything.
Sleep.
Schedules.
Budgets.
The amount of stuff required to leave the house for 45 minutes.
And your financial responsibilities.
If someone now depends on your income—or on work you do at home that someone else would have to replace—it is a good time to look at the protection your household has.
Life insurance may be part of that conversation.
But having a baby does not automatically tell you how much coverage you need.
It gives you better questions.
If something happened to you, what financial responsibilities would still be sitting there?
Housing.
Childcare.
Everyday living expenses.
Education goals.
Debt.
Other family needs.
And if you handle a lot of unpaid work in the household, what would it cost to replace some of that?
You are not trying to guess a magic number.
You are trying to understand what the people depending on you would actually need.
That is a much better place to start.
4. You Bought a Home
You signed approximately 4,700 pieces of paper.
You have keys.
Congratulations.
Now let us talk insurance.
Buying a home obviously changes your property insurance.
But that is not the only thing worth looking at.
You may have just added one of the largest assets you own.
And probably one of the largest debts you owe.
That can change the bigger insurance picture too.
Homeowners coverage.
Liability.
Life insurance.
Flood coverage, depending on the property and location.
Maybe other coverage based on the home itself.
Your mortgage company may have insurance requirements too.
But do not stop at:
“The bank says I have insurance, so we are good.”
The lender is trying to protect its financial interest.
You are trying to protect yours.
Those goals overlap.
They are not always exactly the same.
A better question is:
Now that I own this home, what else in my insurance life deserves another look?
5. You Moved
You do not have to buy a house for a move to matter.
Maybe you are renting.
Maybe you moved across town.
Maybe across the state.
Maybe across the country.
Tell the appropriate insurers.
Where you live can matter.
For auto insurance, where the vehicle is primarily kept can affect the policy.
For renters or homeowners insurance, you are obviously insuring a different place.
Moving can also change your risks.
Different weather.
Different theft exposure.
Different commute.
Different state requirements.
Different property.
Different insurance market.
If you moved and your insurance still thinks you live at the old address, that is something I would fix.
Mail forwarding is useful.
It is not an insurance strategy.
6. Your Teen Started Driving
One day they are learning multiplication.
Approximately twelve minutes later they are asking for the car keys.
Once a teenager reaches the permit or licensing stage, call your auto insurer and ask what it requires.
The timing can vary by insurer and state.
Ask:
When does the teen need to be listed or added?
How might the premium change?
Are there discounts available?
Good-student discount?
Driver-training discount?
Anything else?
And if you are thinking about buying another vehicle for the teen, get insurance quotes before you buy it.
A cheap used car can become considerably less cheap once insurance joins the conversation.
For this article, the point is simple:
New driver in the household = insurance review.
7. You Started a Business or Side Gig
This one is easy to miss.
Maybe you did not launch a company with employees, offices, and a giant sign on the building.
Maybe you started:
Freelancing.
Selling products online.
Consulting.
Working from home.
Driving for a delivery app.
Driving passengers.
Pet sitting.
Photography.
Making products.
Doing repair work.
Something small.
It is easy to think:
“It is just a side gig.”
Your insurance company may still care.
Personal insurance is not automatically built to cover every business activity.
A homeowners or renters policy may have limits involving business property or liability.
A personal auto policy may have restrictions involving certain business, delivery, or rideshare use.
So tell the insurer what you are actually doing.
Then ask:
Does my current insurance cover this activity?
If not:
What would I need to look at?
That is a much nicer question to ask before something goes wrong.
8. Your Financial Situation Changed Significantly
This one can be less obvious.
Maybe you got a big raise.
Paid off major debt.
Built up savings.
Inherited money.
Bought investment property.
Accumulated more assets.
Or maybe things went the other direction.
Income dropped.
Savings got thinner.
Your financial obligations changed.
Your emergency fund changed.
Insurance is partly about deciding which financial risks you can handle yourself and which ones you want help transferring to an insurer.
So if your financial situation changes a lot, some of your old insurance decisions may deserve another look.
Maybe your liability limits no longer feel right.
Maybe your life-insurance needs changed.
Maybe a deductible that once felt impossible is now manageable.
Or maybe the deductible you picked five years ago would be a serious problem today.
This is one of my favorite questions:
If I had to pay this deductible tomorrow, what would happen?
Yes, I could handle it.
It would hurt.
No.
I am not sure.
All four answers tell you something useful.
The goal is not:
More money = buy more insurance.
It is:
Different financial situation = make sure the old decisions still fit.
What About Retirement?
Retirement can absolutely trigger a review too.
Technically, I promised you eight.
I am aware.
But retirement can change enough things that I am sneaking it in anyway.
Your commute may disappear.
Your income may come from different places.
Employer benefits may change.
Health coverage may change.
Life-insurance needs may change.
How you use your vehicles may change.
Where you live may change.
Your assets and financial priorities may change.
So yes.
Retirement belongs on the list.
Consider this number 8½.
We are not changing the title.
What About Buying an Expensive Item?
Also worth checking.
Jewelry.
Art.
Collectibles.
Electronics.
Special equipment.
Other valuable property.
Do not assume your homeowners or renters policy automatically provides unlimited coverage for everything you own.
Certain types of property can have special limits, exclusions, or different rules.
If you make a major purchase, ask:
Does my current policy cover this the way I think it does?
You may need additional coverage depending on the item and policy.
Again:
Ask before the loss.
Much nicer conversation.
A Life Change Does Not Automatically Mean You Need More Insurance
This part matters.
We are not saying:
Got married?
Buy more insurance.
Bought a house?
Buy more insurance.
Got a raise?
More insurance.
That is not the point.
A life change is a review trigger.
Maybe you review everything and say:
“This still works.”
Great.
Review done.
Maybe you discover you are paying for something you no longer need.
Also useful.
Maybe you find a question you never answered.
Now you know what to ask.
Maybe you find a genuine gap.
Now you can investigate it.
The goal is not more insurance.
The goal is insurance that still makes sense for your life.
Sometimes You Just Need Better Questions
One of the hardest parts of reviewing insurance is knowing what to look for.
You know your life changed.
You know the policy has been sitting there for a while.
But then you open it and think:
“Okay…now what?”
Start simple.
Do I know my coverage limits?
Do I know my deductibles?
Do I understand the big exclusions?
Do I know when I last reviewed this policy?
Did I look at it after my life changed?
Could I handle the deductible if I had a claim tomorrow?
Is there something I am just assuming is covered?
That is already useful.
Maybe your policy has not been reviewed in years.
Maybe you bought something valuable.
Maybe a beneficiary needs attention.
Maybe you started using your car differently.
Maybe your deductible no longer fits your finances.
Maybe you simply do not know the answer.
That gives you something real to bring to your insurer or licensed insurance professional.
The Insurance Checkup Workbook Can Help You Organize It
If you want more structure, the Insurance Checkup & Quote Comparison Workbook is built for exactly this kind of review.
It helps you slow down and look at the whole picture.
What insurance do I already have?
What changed?
What do I actually know about my policies?
Could I handle the deductibles?
What questions do I still need to ask?
It also helps you think through the people, property, income, debts, and responsibilities you are trying to protect.
And if your review turns into shopping, there are comparison sections for putting quotes side by side without reducing the whole decision to:
“Which one is cheapest?”
Because cheaper is useful information.
It just is not the only information.
You Do Not Need to Review Everything Every Tuesday
Please do not turn this into another task that follows you around.
You do not need to open every insurance policy every time your life moves slightly to the left.
We are looking for meaningful changes.
Ask yourself:
Did something change about what I own?
Did something change about who depends on me?
Did something change about where or how I live?
Did something change about how I use my property?
Did something change about the financial risk I could handle myself?
If yes?
Probably worth a look.
So…When Should You Review Your Insurance?
When something big changes.
Marriage.
Divorce.
A new dependent.
Buying a home.
Moving.
A teen driver.
Starting a business or side gig.
A major financial change.
And yes, retirement and expensive purchases deserve attention too.
You do not need to assume something is wrong.
You do not need to buy anything immediately.
Pull out the policies.
Look at what changed.
Write down your questions.
If you want help organizing the review, use the Insurance Checkup & Quote Comparison Workbook.
Then talk to the appropriate insurer or licensed professional.
Because insurance does not need your attention every day.
But when your life changes?
It is worth making sure the insurance you bought for your old life still makes sense for the one you are living now.
Want a Little More Help?
A life change does not automatically mean you need different coverage, but it is a good reason to ask better questions about what you already have.
Want a simple free tool to help with the next step?
Get the free Insurance Questions Checklist.
Want to go a little deeper?
Take a look at Let’s Talk About Insurance.
Want practical insurance, money, and everyday-life help in your inbox?
Join Emma’s Mailbox.
This article is for general educational and informational purposes only and is not individualized insurance, financial, legal, tax, health, or estate-planning advice. Insurance needs, coverage, eligibility, policy terms, and requirements vary by individual circumstances, insurance type, insurer, and state. Major life events may also involve legal, tax, benefits, estate-planning, or other considerations beyond insurance. Review your own circumstances and contact the appropriate insurer, licensed insurance professional, benefits administrator, attorney, tax professional, financial professional, state insurance regulator, or other qualified professional when appropriate.