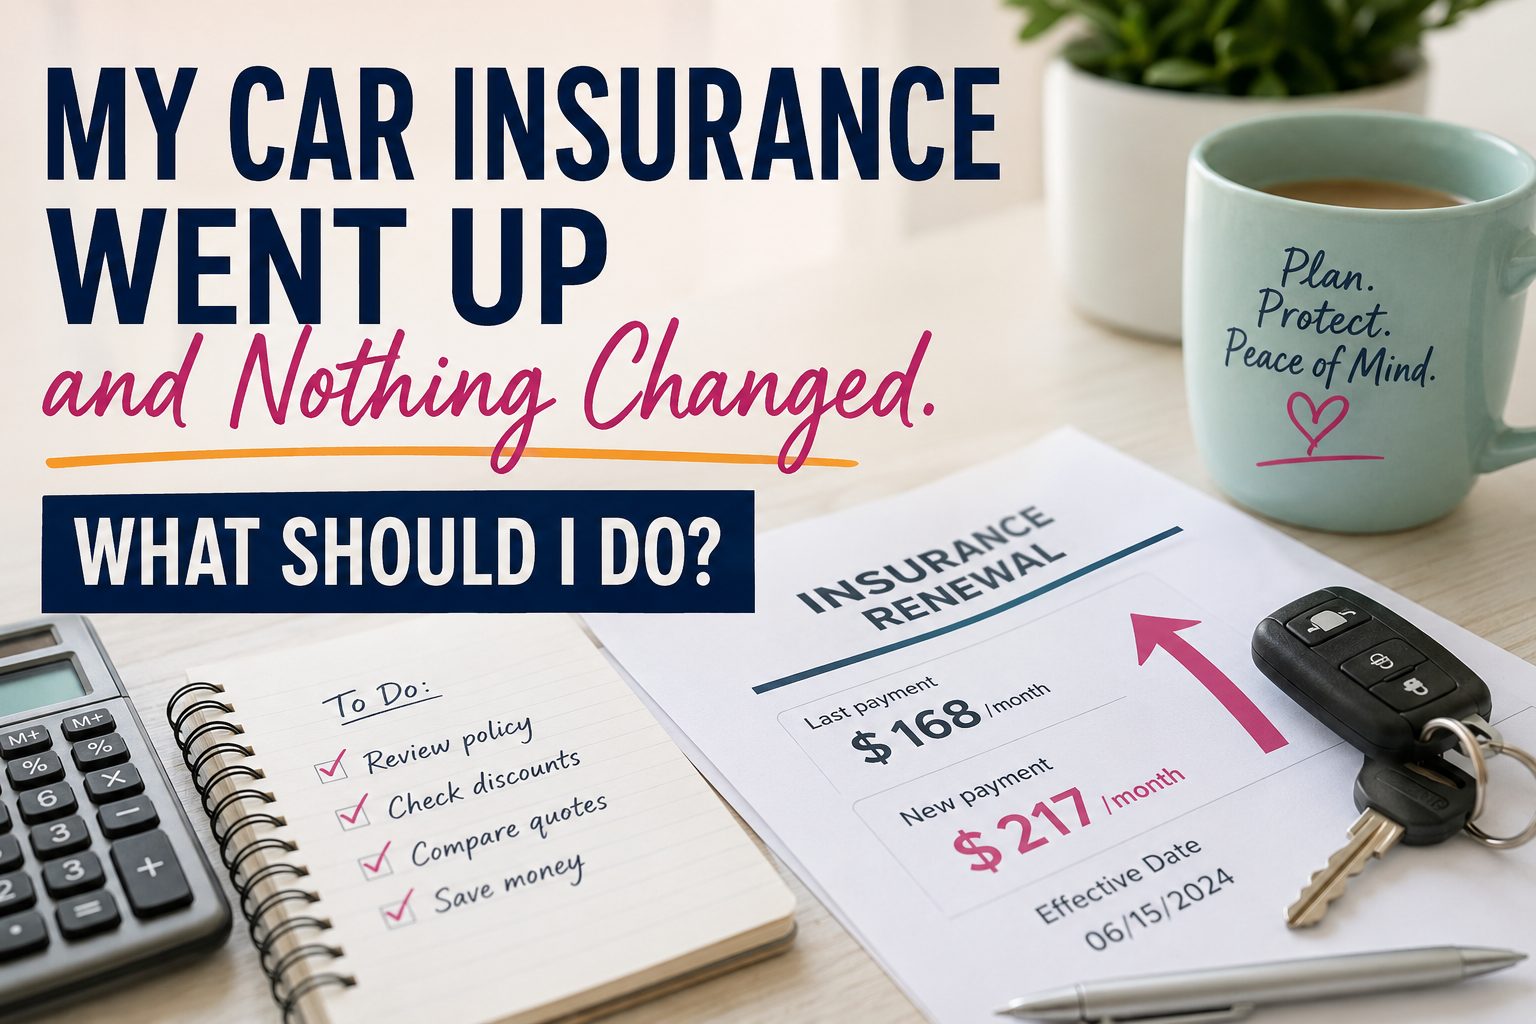
Your car insurance renewal showed up.
Last time: $168 a month.
New price: $217.
Okay.
That’s not a rounding error.
So naturally, you start going through the list.
Accident? No.
Ticket? No.
New car? No.
New driver? No.
Moved? Nope.
Same car. Same house. Same person who was apparently perfectly acceptable to insure six months ago.
So why are you suddenly paying more?
Here’s the frustrating answer:
You may not have done anything.
But before you get mad, cancel the policy, or spend the afternoon collecting twelve different quotes, let’s figure out what actually changed.
Start With the Renewal—Not Just the Price
The new premium is obviously the part that got your attention.
But don’t stop there.
Pull out your current policy information and the renewal. We’re going to compare them side by side.
Look at:
- Vehicles
- Drivers
- Coverage limits
- Deductibles
- Discounts
- Vehicle use or mileage, if shown
- Address or garaging information
- Optional coverages
- And, finally, the premium
If some of those terms aren’t familiar yet, the Insurance Terms Cheat Sheet can help while you work through the policy.
We’re trying to answer one question:
Did your price change because something on your policy changed, or did the price change even though the policy basically stayed the same?
Those are two different conversations.
Make Sure Nothing Actually Did Change
I know.
You already said nothing changed.
Check anyway.
Insurance companies use more information than simply whether you crashed the car or got a ticket.
Maybe a discount disappeared.
Maybe the estimated mileage changed.
Maybe a driver is classified differently.
Maybe something about the vehicle information changed.
Maybe a discount expired.
Maybe the way you pay changed.
Or maybe there’s simply an error.
That’s why I’d look at the policy before calling anyone.
You want to be able to say:
“I’m comparing my old policy with the renewal, and I don’t see any meaningful change in my coverage or information. Can you explain what’s causing the increase?”
That’s a much more useful question than:
“Why did my insurance go up?”
Check Your Discounts
This one deserves its own stop.
Look at the discounts on the old policy.
Now look at the renewal.
Are they all still there?
You might see things like a safe-driver discount, multi-policy discount, multi-car discount, low-mileage discount, good-student discount, automatic-payment discount, or something else offered by your insurer.
Discounts vary by company and state, so we’re not assuming you should have any particular one.
We’re checking whether something you already had disappeared.
And while you’re at it, ask:
“Are there any discounts I’m eligible for that aren’t currently applied?”
Simple question.
Worth asking.
Now Call the Insurance Company or Agent
This is where we find out what’s going on.
Have the renewal in front of you and ask:
“Can you walk me through why my premium increased?”
You don’t need to know all the insurance terminology.
You don’t need to argue.
You just want an explanation.
If the answer is, “Rates increased in your area,” okay.
Then ask whether there were any changes specific to your policy.
If they mention a driver, vehicle, claim, mileage, or another factor, make sure the information is accurate.
If something is wrong, ask what they need from you to correct it.
And if everything is right and the rate simply increased?
Well, now we know what problem we’re actually solving.
We may not like the answer.
But at least we have one.
Yes, Your Rate Can Go Up Even If You Didn’t Have an Accident
This is one of the things that frustrates people most about insurance.
You can drive carefully, avoid tickets, file no claims—and still get a higher renewal.
Why?
Because your premium isn’t based only on what happened to you personally.
Insurance companies are also estimating the cost of future claims. If vehicles become more expensive to repair, parts and labor cost more, medical claims become more expensive, theft patterns change, or losses increase in an area, those costs can eventually affect premiums.
That doesn’t mean every increase automatically makes sense for your situation.
And it certainly doesn’t mean you shouldn’t shop around.
It just means:
“But I didn’t have an accident” isn’t the only thing affecting the price.
Don’t Immediately Start Cutting Coverage
Your premium went up $50 a month.
You want that $50 back.
Understandable.
So maybe you start looking at the policy and thinking:
Higher deductible?
Lower liability limit?
Drop rental reimbursement?
Remove collision?
Hold on.
We can review all of those things.
But don’t start removing coverage simply because you’re angry about the price.
Every change has another side.
Raise the deductible?
Your premium may go down, but you’re agreeing to take on more of the cost after certain claims.
Lower a limit?
You may be keeping more of the financial risk yourself.
Remove a coverage?
Make sure you understand what problem that coverage was handling before you decide you no longer want it.
The goal isn’t:
Make the premium number smaller at any cost.
The goal is:
Pay a reasonable amount for coverage that still makes sense for you.
Now Look for Ways to Lower the Bill
Once you know the policy information is correct, start with the easier possibilities.
Ask about discounts.
Review how many miles you’re driving.
Make sure the vehicle-use information is accurate.
Look at optional coverages.
Ask what changing your deductibles would do to the premium.
If you have more than one policy, ask whether bundling changes anything.
But whenever you’re offered a change, ask one more question:
“What am I giving up to save this money?”
Sometimes the answer is:
Nothing. You found a discount.
Wonderful.
Sometimes the answer is:
You’re taking on another $500 of deductible.
That’s different.
Savings aren’t really savings until you understand the tradeoff.
And Yes, This May Be the Time to Shop
Sometimes you do everything above and reach a very simple conclusion.
Your insurer wants $217 a month.
You’d like to know whether somebody else wants less.
Fair enough.
Get some quotes.
But please don’t compare only this:
Company A: $217
Company B: $181
Company C: $159
Looks like Company C wins.
Maybe.
Before we hand them the trophy, we need to know what they’re actually quoting.
Compare the Coverage Before You Compare the Price
This is where insurance shopping can get messy.
One quote might have higher liability limits.
Another might have lower limits.
One might have a $500 deductible.
Another has $1,000.
One includes rental reimbursement.
Another doesn’t.
One includes a coverage you had before.
Another leaves it out.
Suddenly, $159 versus $217 isn’t really a comparison.
It’s two different products with two different prices.
That’s exactly why we created the Insurance Checkup & Quote Comparison Tool.
Put the quotes next to each other and compare:
- Limits
- Deductibles
- Coverages
- Options
- Then price
You don’t have to choose the quote with the most coverage.
And you don’t automatically have to choose the cheapest one.
You just need to understand what you’re choosing.
Be Careful About Raising Your Deductible Just to Lower the Premium
Raising a deductible is a common way to reduce the price.
And sometimes it makes perfect sense.
Suppose changing your collision deductible from $500 to $1,000 saves you money.
Great.
But I want you to ask yourself something else:
If you had a covered collision next Tuesday, could you reasonably handle that $1,000 deductible?
If the answer is yes, maybe that tradeoff deserves consideration.
If the answer is:
“I’d have to put the deductible on a credit card,”
then we should think a little harder.
The cheapest insurance decision today can become an expensive problem later.
Don’t Cancel the Old Policy Too Early
You found another insurer.
The coverage looks good.
The price is better.
Excellent.
Before cancelling your current policy, make sure the new coverage is actually set to begin.
Check the effective date.
Make sure you’ve completed everything the new insurer requires.
Then coordinate the cancellation of the old policy.
We do not want:
Old policy ends Friday.
New policy begins Monday.
Saturday and Sunday suddenly become extremely exciting.
Avoid the lapse.
What If the Other Quotes Aren’t Any Better?
That can happen too.
You get three quotes.
Maybe four.
And they’re all expensive.
That’s useful information.
It suggests your current insurer may not be uniquely expensive.
At that point, we have to look at the bigger picture.
Can you comfortably handle the premium?
Are there reasonable changes available?
Could you increase a deductible without creating another financial problem?
Are there expenses elsewhere that could be adjusted?
This is where auto insurance stops being only an insurance question and starts becoming a money question.
You need the coverage.
But you also have to be able to afford it.
Don’t Shop Yourself Into Worse Insurance
This is the part I really want you to remember.
A lower premium feels like a win.
And it can be.
But saving $38 a month isn’t much of a victory if you accidentally gave up something you would have wanted after a serious accident.
So slow down.
You don’t have to understand every sentence in an insurance contract before you can shop intelligently.
You do need to understand the major choices you’re making.
That’s one of the reasons we’re putting together Let’s Talk About Auto Insurance.
The book goes much deeper into what the different coverages actually do, how limits and deductibles work, why premiums change, and what to think about when you’re deciding what protection makes sense for you.
But you don’t need the whole book to deal with today’s renewal.
Today, you need a plan.
So Your Car Insurance Went Up. Now What?
Don’t panic.
Don’t immediately cancel.
And don’t start randomly removing coverage.
Do this instead:
- Compare the old policy with the renewal.
- Make sure the drivers, vehicles, and other information are correct.
- Check your discounts.
- Ask why the premium changed.
- Ask what options might lower it.
- Understand the tradeoffs before changing coverage.
- Get a few comparable quotes if the price still doesn’t make sense.
- Use the Insurance Checkup & Quote Comparison Tool so you’re comparing the same things.
- Then decide whether staying or switching makes more sense.
Maybe you find a much better price.
Maybe you discover a missing discount.
Maybe you make a reasonable adjustment.
Maybe you decide your current policy is still the best option available.
Any of those can be a good outcome.
Because the goal wasn’t simply to get a cheaper number.
The goal was to understand why the number changed and make a deliberate decision about what to do next.
That’s a much better response than staring at the renewal and wondering:
What did I do?
Maybe nothing.
Now let’s see what you can actually do about it.
This article is for general educational and informational purposes only and isn’t intended as individualized insurance, financial, legal, or tax advice. Insurance coverage, pricing, requirements, and policy terms vary by insurer, policy, and state. Review your own policy and circumstances, and contact your insurance company, licensed insurance professional, state insurance regulator, or another qualified professional when appropriate.