Most of us have some kind of system for paying the bills.
It may be a very organized system with a spreadsheet, calendar, and automatic payments.
It may be a stack of envelopes on the counter.
Or it may be a system that mostly lives in your head.
You know the electric bill comes out around the 12th. You know which credit card pays for the streaming services. You know the car insurance is automatic, but the water bill isn’t. You know which bill sometimes changes and which account needs a little extra money before payday.
That can work perfectly well—until you’re suddenly not available to handle it.
What would happen if you couldn’t take care of the household finances for the next 30 days?
Not forever.
Just a month.
Maybe you’re in the hospital. Maybe you have to leave town unexpectedly to help a family member. Maybe you’re sick enough that keeping track of due dates is the last thing you want to think about.
Would someone else know what needs to be done?
The Problem Isn’t Always the Money
When we talk about preparing for emergencies, we tend to think about having enough money.
That’s important, but there’s another problem that gets much less attention:
Does anyone else know how your household actually works?
You can have plenty of money sitting in the bank and still end up with a late payment if nobody knows a bill needs to be paid.
You can have automatic payments set up and still have trouble if nobody knows which account they’re coming from.
You can have excellent insurance and still miss a premium notice because you’re the only person who checks that email account.
A household develops dozens of little routines like these.
Usually, we don’t notice how much information we’re carrying around until someone else has to take over.
Start With the Bills That Keep the Household Running
You don’t need to document every purchase you’ve ever made.
Start with the things that would cause a real problem if nobody handled them for a month.
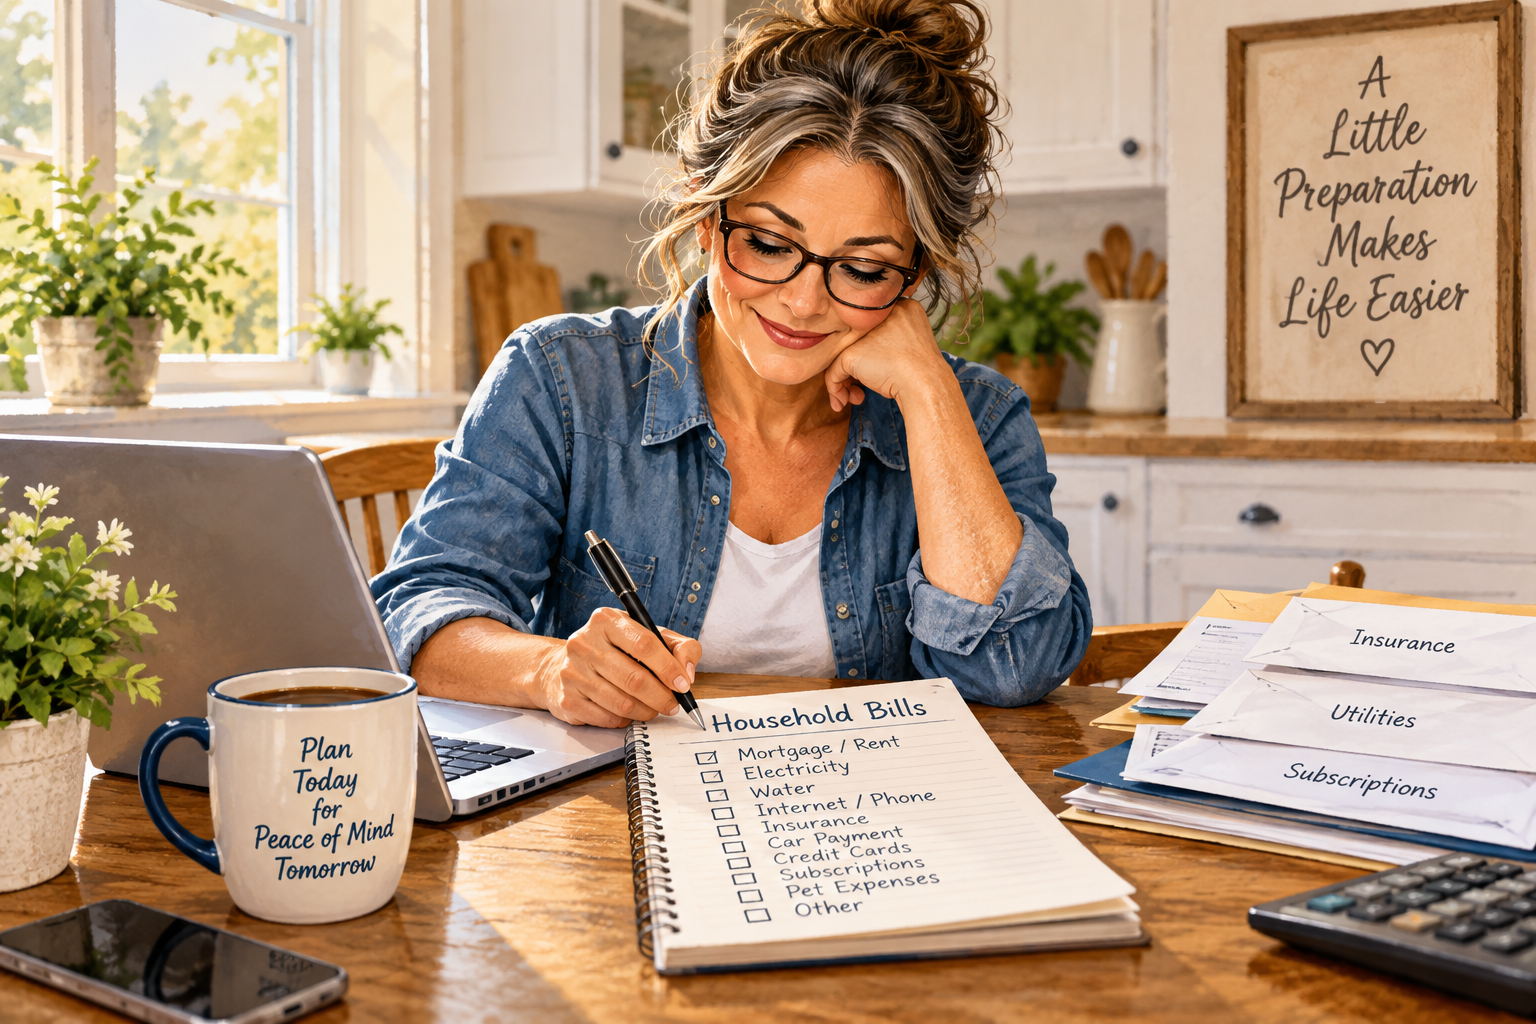
- Mortgage or rent
- Electricity
- Water
- Gas
- Internet and phone service
- Insurance premiums
- Car payments
- Credit cards
- Loan payments
- Childcare
- Regular medical expenses
- Pet expenses
- Important subscriptions or services
Your list will probably look different from someone else’s. That’s fine.
The goal isn’t to create the perfect household-finance binder. The goal is to make sure another person could look at your information and understand what needs attention.
Write Down How Each Bill Is Paid
Next to each bill, write down a few basic details.
When is it normally due?
You don’t necessarily need the exact date if it changes. “Middle of the month” may be enough to remind someone to check.
Is it paid automatically?
This matters because an automatic payment doesn’t mean a bill can be ignored. Someone still needs to make sure there’s enough money in the account.
Where is the bill normally found?
Does it arrive by mail? Email? An app? Does someone have to log into an online account to see it?
That little piece of information can save someone a surprising amount of detective work.
Don’t Put Sensitive Information on the List
There’s an important difference between making a useful household guide and creating a piece of paper containing everything someone would need to steal your identity.
Your basic bill list doesn’t need to include full bank account numbers, credit card numbers, Social Security numbers, PINs, or passwords.
Instead, the list might say:
Electric company — automatic payment — checking account — around the 14th
or
Car insurance — paid manually — bill comes by email — due near the end of the month
That’s enough to tell someone what exists and where to start.
Sensitive information should be stored separately and securely.
Check Your Automatic Payments
Automatic payments make life easier, but they’re worth reviewing as part of this exercise.
Ask yourself: If I didn’t touch my finances for 30 days, would there be enough money in the account to cover everything scheduled to come out?
This is especially important if you normally move money between accounts throughout the month.
For example, maybe your mortgage, insurance, and utilities all come from checking, but you normally transfer money into that account every payday.
Someone looking at your bank balance might assume everything is handled because the bills are automatic.
It isn’t if the money that normally funds those payments never gets moved.
Write down the routine, not just the bill.
Think About the Things That Aren’t Bills
Some household responsibilities don’t arrive with a due date.
Maybe someone needs to refill a prescription. Maybe the dog gets medication every month. Maybe you regularly order supplies for an older family member. Maybe a child has an activity that requires a monthly payment. Maybe the propane tank needs to be watched. Maybe there’s a service you have to schedule rather than simply pay.
Ask yourself: What do I routinely remember so nobody else has to?
Those are exactly the things another person may not know about.
Decide Who Should Know This Information Exists
Creating the list doesn’t help very much if nobody knows where it is.
You don’t necessarily need to hand copies to several people.
You do need at least one trusted person who knows something like: “If something happens and I can’t handle things for a while, here’s where I keep the household information.”
Depending on your situation, that might be your spouse or partner, an adult child, a parent, a sibling, or another person you trust.
The right person is going to be different for every household.
Try the 30-Minute Test
You don’t need to turn this into an all-day project.
Set aside about 30 minutes and see how much you can identify.
- Your recurring household bills
- Approximately when they’re due
- Which ones are automatic
- Where the bills or notices arrive
- Which account normally pays them
- Regular responsibilities that aren’t traditional bills
- Where important household information is stored
- Who should know this list exists
Then look at it from the perspective of someone who doesn’t normally handle your finances.
Would they know what to do next?
If not, add the missing explanation.
This Isn’t About Planning for the Worst
You don’t need to imagine some terrible disaster to make this useful.
Sometimes life is simply inconvenient.
People get sick. Family emergencies happen. Trips get extended. Phones break. Passwords get forgotten.
The person who normally handles everything occasionally needs someone else to take over.
A little organization now can make that much easier.
And there’s another benefit.
Once you put everything in one place, you may discover things about your own finances that you’ve stopped noticing.
A subscription you don’t use. A bill that would be easier on autopay. An automatic payment coming from the wrong account. A service you forgot you were paying for. Or simply a household system that makes much more sense in your head than it does on paper.
That’s useful information even if nobody else ever has to use your list.
One Small Step This Week
You don’t have to build an emergency binder today.
Start smaller.
Make the recurring-bill list.
That’s it.
Once you’ve done that, you have something you can improve over time instead of a project you’ve been meaning to start someday.
And if you’re thinking more broadly about what your household would need when normal routines get interrupted, Let’s Talk About Emergencies walks through practical ways to prepare before you’re dealing with the emergency itself.
Friendly conversations. Practical tools. Clear explanations.
— Emma
Want a Little More Help?
If this has you thinking about how your household money is organized, you do not have to rebuild your whole system today. Start with one useful next step.
Want a simple free tool to help with the next step?
Get the free Monthly Money Check-In.
Want a clearer, beginner-friendly way to work through your money?
Take a look at Let’s Talk About Money.
Want practical insurance, money, and everyday-life help in your inbox?
Join Emma’s Mailbox.