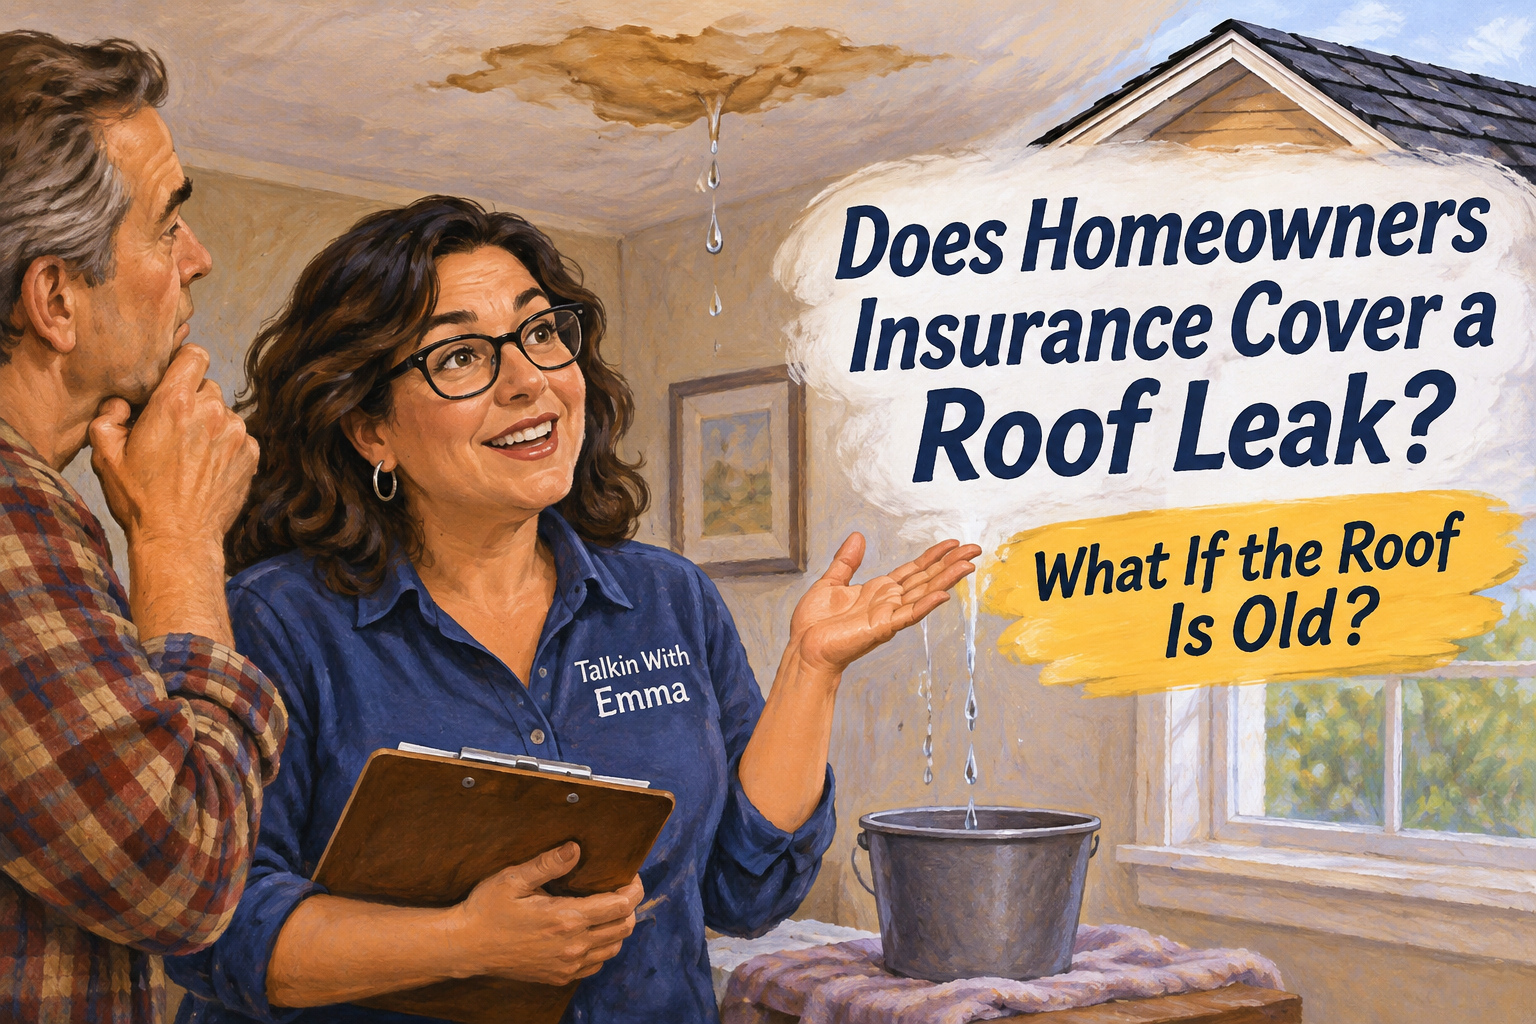
You notice a brown spot on the ceiling after a heavy rain. Maybe there’s a drip near the window, or you find a damp patch in the attic. Your first thought might be, “Will homeowners insurance pay for this?”
The answer is: sometimes. Homeowners insurance may cover damage from a roof leak when the leak was caused by a sudden event your policy covers, such as wind or hail. But it generally doesn’t pay to fix a roof that has simply worn out over time.
What caused the roof to leak?
Imagine two neighbors, Maria and David. Both discover water stains on their ceilings after a storm. Maria’s roof lost shingles in strong wind, letting rain enter. David’s roof has had cracked, aging shingles for years, and water has slowly worked its way inside.
Their ceilings look similar, but their insurance claims may turn out very differently. If wind is a covered cause of loss under Maria’s policy, the resulting roof and interior damage may be covered, subject to the deductible and policy terms. David’s worn-out roof is more likely to be treated as a maintenance issue.
That’s why an insurance adjuster will want to know not just where the water came in, but why it came in.
Does insurance cover a roof leak caused by a storm?
Often, yes, if the storm caused damage covered by your policy. For example, wind might tear off shingles or a falling tree might damage the roof. Water that enters through that storm-created opening may also damage insulation, drywall, flooring, or belongings.
But coverage is not automatic. Some policies have special wind or hail deductibles, roof-payment limits, exclusions, or rules about how roof age affects the settlement. Your location and policy matter.
What if my roof is old?
An old roof isn’t automatically uninsured. A covered storm can damage an older roof, too. But insurance generally isn’t designed to replace a roof simply because it has reached the end of its useful life.
Another important detail is how the insurer values the roof. Some policies pay replacement cost when their conditions are met. Others pay actual cash value, which accounts for depreciation, or use a roof-specific payment schedule. That can leave you paying much more out of pocket than you expected.
For example, if a covered repair costs $10,000 and your policy has a $2,000 deductible, that doesn’t necessarily mean you’ll receive $8,000. Depreciation, roof endorsements, limits, and other terms can change the amount. Ask your insurer for a written explanation of the settlement.
What about the water damage inside the house?
Sometimes the roof repair and the interior damage are evaluated separately. Even if the roof itself isn’t covered because of wear and tear, certain resulting interior damage may be covered under some policies, depending on the cause and wording. Other policies may exclude that damage as well.
Don’t assume that a denied roof repair means every part of the claim must be denied—or that interior damage is automatically covered. Ask the insurer to explain each decision and the policy language behind it.
What should I do when I discover a roof leak?
First, protect people and property. Stay away from sagging ceilings and electrical hazards. If it’s safe, move belongings out of the wet area, catch dripping water, and arrange reasonable temporary protection to prevent further damage. Don’t climb onto a wet or damaged roof.
Next, take pictures and short videos of the leak, the stained ceiling, damaged belongings, and any visible storm damage you can photograph safely from the ground. Write down when you first noticed the problem and any recent storms.
Contact your insurance company or agent promptly to ask about reporting the loss, your deductible, and whether emergency repairs need approval. Keep receipts for temporary work. Avoid making permanent repairs or throwing away damaged materials before the insurer has had a reasonable chance to inspect, unless safety requires immediate action.
If you hire a roofer, get a written inspection and estimate. Be cautious of anyone who promises that insurance will definitely buy you a new roof or pressures you to sign over claim rights before you understand the paperwork.
Should I file a claim for every roof leak?
Not necessarily. Find out the likely cause, the estimated repair cost, and your deductible before deciding when possible. If the repair is smaller than your deductible, there may be no claim payment. And claims can affect future premiums or renewal decisions, depending on the circumstances and state rules.
For more on that last point, read Can My Insurance Company Cancel My Policy After I File a Claim?.
Questions to ask your insurance company
You don’t need to know every insurance term. Start with these questions: What caused the damage according to the inspection? Is wind or hail damage covered? Is my roof settled at replacement cost, actual cash value, or on a payment schedule? Is there a separate wind or hail deductible? Is the interior water damage covered? What documents do you need from me?
Ask for the answers in writing, especially if part of the claim is denied.
The bottom line
A roof leak isn’t automatically covered or excluded. The cause of the leak, the type of damage, and the wording of your policy are what matter. A sudden covered storm event is different from years of wear and neglected repairs.
And if you’re unsure what your policy actually says, that’s a good reason to review it before the next storm. You can start with a 15-minute insurance checkup, or explore how homeowners insurance handles a broken water pipe.
You don’t have to become an insurance expert. You just need to know what to ask, what to document, and where to find the answer in your own policy.
Important note: This article provides general educational information, not a coverage determination. Insurance coverage depends on your policy, endorsements, exclusions, and applicable state law.